Turn Business Income Into Personal Wealth
Personal Finance, Financial Systems, Wealth Building
Turning Business Income Into Personal Wealth: From Cash Flow to Freedom
You started a business to create freedom, not just another demanding job. Yet many entrepreneurs stay stuck in the cycle of income generation—chasing the next sale, the next contract, the next launch—without ever turning that effort into lasting personal wealth. This guide from Big Life Financial will help you move beyond income, build durable financial systems, and avoid the most common wealth transfer mistakes that quietly drain your future.
Why Income Generation Isn’t Enough
Many business owners quietly believe a dangerous myth: “If I just grow my income, wealth will take care of itself.” It feels logical—more revenue, more profit, more money in your account. But income alone is not a wealth strategy. It’s only the raw material. Without a clear plan and solid financial systems, higher income can actually create more complexity, more tax, and more lifestyle creep, not more freedom.
Think of your business as a powerful engine. Income generation is the horsepower. Personal wealth is the destination. Between the two, you need a transmission—a set of intentional processes that convert business profits into assets that work for you, even when you’re not working. That “transmission” is your personal financial system.
💡 Big Life Financial Insight: High income without a plan is just a more expensive version of living paycheck to paycheck.
Step 1: Separate the Business You Run from the Life You Live
The first move beyond income generation is to clearly separate your business finances from your personal finances. This sounds basic, yet many entrepreneurs blur the lines—paying personal expenses from business accounts, “borrowing” from the company, or leaving everything piled up in a single checking account. That makes it almost impossible to build real wealth or see where your money is actually going.
Open distinct business and personal accounts, each with a clear purpose.
Decide on a consistent owner’s pay or salary, even if it fluctuates seasonally.
Treat your business like a separate entity that must stand on its own.
When you create that separation, you can start asking smarter questions: “How much of my income should flow into long-term assets?” “What is my personal savings rate?” “How can I design my lifestyle so it doesn’t consume every dollar the business produces?”
Step 2: Design a Simple, Automatic Financial System
A powerful financial system doesn’t have to be complicated. In fact, the best systems are often simple, visual, and largely automated. The goal is to turn your business income into predictable flows toward your priorities: security, growth, and eventually, freedom from needing to work in the business at all.
The Four Core Buckets of a Wealth-Building System
Stability Bucket: Emergency reserves for both business and personal life—typically 3–6 months of expenses each. This protects your wealth plan from being derailed by short-term surprises.
Growth Bucket: Investments that are designed to grow over time—retirement accounts, brokerage accounts, cash-flowing real estate, or other assets that don’t depend on your daily presence to produce income.
Tax Strategy Bucket: Structures such as retirement plans, insurance-based strategies, or legal entities that help you keep more of what you earn instead of losing it to unnecessary taxes.
Legacy Bucket: Tools like trusts, beneficiary designations, and intentional gifting that support a smooth wealth transfer to the people and causes you care about.
The magic isn’t just in having these buckets—it’s in automating how your income flows into them. At Big Life Financial, we often help clients create a rhythm such as: a fixed percentage of every owner’s draw goes directly into long-term investments, another percentage to tax reserves, and another to a “future freedom” account that will eventually replace active income.
💡 Pro Tip: If you have to decide every month how much to save or invest, you’ll lose that battle to emotion and busyness. Let systems, not willpower, build your wealth.
Step 3: Turn Business Success into Personal Assets
Once your financial system is in place, the question becomes: What are you actually building with your income? Many entrepreneurs reinvest everything back into the business, assuming that’s always the highest return. Sometimes it is. But concentrating all your wealth in a single, illiquid, high-risk asset—your own company—can leave you vulnerable if markets shift or you simply burn out.
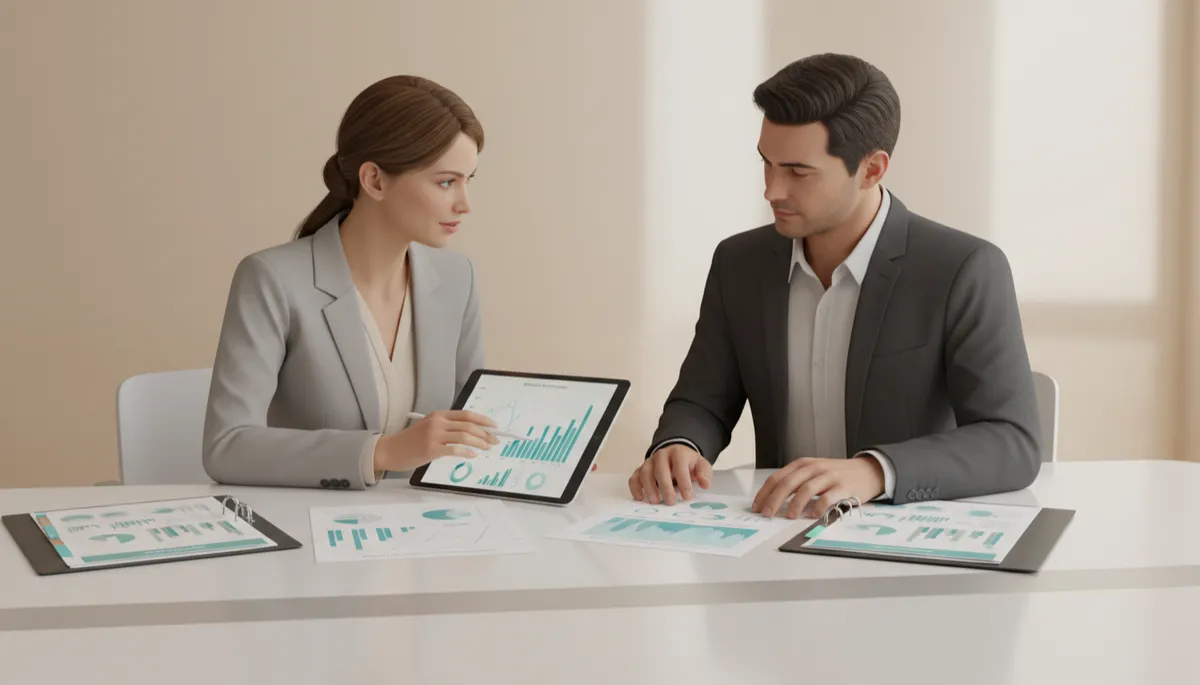
-toned photo of a financial consultant and business owner sitting at a modern table reviewing...
Translating business profits into diversified assets lowers risk and increases long-term flexibility.
A healthier approach is to use business success to create multiple streams of personal wealth. That might include:
Retirement accounts that reduce current taxes and grow for future income.
A diversified investment portfolio that isn’t tied to your industry’s ups and downs.
Real estate that can provide both appreciation and rental income over time.
Strategic insurance and legal structures that protect your assets from lawsuits, creditors, and other risks.
The goal is simple: use your business income to buy back your time. Over the years, your financial system should gradually shift you from “I have to work” to “I choose to work,” because your assets are generating enough income to support your lifestyle.
Avoiding the Most Common Wealth Transfer Mistakes
Building wealth is only half the journey. The other half is keeping it in your family or aligned with your values instead of losing it to taxes, conflict, or poor planning. This is where many successful entrepreneurs make costly wealth transfer mistakes—often without realizing it until it’s too late.
Mistake #1: Relying Only on a Simple Will
A basic will is better than nothing, but it often doesn’t address the complexity of business ownership, blended families, or significant assets. A will typically goes through probate, which can be slow, public, and expensive. It may also fail to coordinate with beneficiary designations on retirement accounts, life insurance, or business agreements—creating confusion and unintended outcomes.
📌 Key Takeaway: As your wealth grows, your estate plan should evolve from “basic documents” to an integrated strategy that includes trusts, updated beneficiaries, and clear instructions for business interests.
Mistake #2: Ignoring Tax-Efficient Wealth Transfer
Without planning, a significant portion of what you’ve built can be lost to taxes when it’s transferred to the next generation. While rules vary by country and state, there are often strategies—such as lifetime gifting, trusts, and properly structured life insurance—that can dramatically reduce that impact. The problem isn’t that tools don’t exist; it’s that busy entrepreneurs rarely take the time to design a proactive plan.
Working with a financial consultant like Big Life Financial and a qualified tax professional can help you spot opportunities to move assets in ways that are both legal and efficient, so your wealth goes to people and causes you choose—not just to the government by default.
Mistake #3: Transferring Wealth Without Transferring Wisdom
One of the most overlooked wealth transfer mistakes is giving money to heirs who aren’t prepared to handle it. Studies consistently show that a large percentage of inherited wealth is gone within a generation or two. The issue usually isn’t bad intent—it’s a lack of financial education, shared values, and clear expectations.
Talk openly with your family about money, values, and the purpose of your wealth.
Involve adult children in age-appropriate conversations with your advisors.
Consider structures that release funds over time or based on milestones, instead of all at once.
When you pair financial assets with financial wisdom, you give the next generation a genuine head start instead of an overwhelming windfall.
Mistake #4: No Clear Plan for the Business Itself
Your company may be your largest asset, but what happens to it if you retire, become disabled, or pass away unexpectedly? Without a buy–sell agreement, succession plan, or clear instructions, your family may be forced to sell the business quickly—often at a discount—or step into roles they’re not prepared for.
A thoughtful exit and succession strategy is a crucial part of your personal finance plan. It can turn years of effort into a meaningful payoff that supports your long-term lifestyle and your legacy goals.
Aligning Your Money with the Life You Actually Want
Turning business income into personal wealth isn’t just about numbers; it’s about clarity. Before you can design the right financial systems, you need a picture of the life you’re building. Do you want to step back from your business in ten years? Travel more while still earning? Fund your kids’ education or support specific causes? Your answers shape how aggressively you save, what you invest in, and how you structure your wealth transfer plan.
💡 Big Life Question: If your business suddenly paid you enough to never work again, what would you actually do with your time? Your financial plan should move you toward that answer.
Once you’re clear on your vision, you can reverse-engineer the numbers. How much annual income will you need? What level of assets could reasonably produce that income without depleting the principal? From there, your income generation becomes a tool to fund a very specific target, rather than an endless race for “more.”
Putting It All Together: A Practical Roadmap
Clarify your vision. Define what financial freedom and a “big life” mean for you personally, beyond just a number in the bank.
Separate business and personal finances. Create clean accounts, consistent owner’s pay, and visibility into where your money goes.
Build your financial system. Set up automatic flows into stability, growth, tax, and legacy buckets so your wealth builds by default.
Diversify your personal assets. Use business profits to create investments that can eventually replace active income.
Plan your wealth transfer. Work with professionals to avoid common wealth transfer mistakes, minimize taxes, and align your plan with your values.
Review and adjust regularly. Life changes, tax laws change, and your business evolves. Revisit your plan at least annually to keep it aligned and effective.
From Busy Owner to Intentional Wealth Builder
You don’t have to become a financial expert to build meaningful wealth from your business. You simply need a clear vision, a few smart financial systems, and the willingness to move beyond short-term income generation. When you do, every sale, every contract, and every new client becomes more than just revenue—it becomes another building block in a life of choice, security, and impact.
At Big Life Financial, we believe your business should be a bridge to the life you want, not a cage that keeps you trapped. By intentionally converting business income into long-term assets, and by avoiding the wealth transfer mistakes that erode so many family fortunes, you can create a legacy that lasts far beyond your working years.
The next step is simple: choose one idea from this guide and implement it this month—whether that’s opening a separate account, automating a transfer into investments, or booking a conversation with a financial consultant. Small, consistent actions are how real wealth is built. Your business is already working hard. It’s time to make sure your money is, too.
If this article gave you a few things to think about, there’s more to explore. Take some time to watch the video and hear the ideas come together through a deeper conversation, with additional perspectives and insights that can add to what you’ve just read.
