
Teaching Financial Responsibility to Youth
Financial Responsibility, Money Management, Youth Education, Corporate Social Impact
Businesses and agencies are uniquely positioned to shape how the next generation understands money, risk, and opportunity. Moving beyond one-off workshops and classroom lectures, forward-thinking organizations are now designing structured, real-world experiences that build financial responsibility from an early age. By offering controlled exposure to money, allowing small mistakes, and creating meaningful work opportunities, companies can help young people develop the money management competence they will need as adults—while also advancing their own brand, talent pipeline, and social impact goals.
Why Financial Responsibility Must Start with Real Money, Not Just Theory
Most young people encounter money long before they encounter structured financial education. They see parents swipe cards, tap phones, or click “buy now,” but rarely get to experience the full cycle of earning, budgeting, spending, and reflecting on outcomes. For organizations committed to fostering long-term financial responsibility, this gap is both a challenge and an opportunity. It highlights the need to move from abstract lessons to controlled exposure to money, where children and teens handle real funds under guidance and clear boundaries.
Research and practical experience consistently show that money management skills are best learned through doing. When young people are trusted with real decisions—however small—they begin to internalize concepts like trade-offs, delayed gratification, and risk. Businesses and agencies can accelerate this learning by designing programs that give young participants responsibility over budgets, micro-earnings, or simple business tasks, all within a framework that limits downside and magnifies learning.
The Strategic Value for Businesses and Agencies
Supporting youth financial responsibility is not only a social good; it is also a strategic move for organizations. Companies that invest in real-world financial education initiatives often see benefits in multiple areas:
Brand trust and reputation: Demonstrating a tangible commitment to financial literacy and responsible money management elevates corporate credibility with customers, regulators, and communities.
Future talent pipeline: Young people who learn to manage money responsibly are more likely to become reliable employees, partners, and even entrepreneurs within your ecosystem.
Customer education: Financially competent customers are better equipped to use your products appropriately, reducing complaints, defaults, and reputational risk over time.
Regulatory alignment: Many regulators increasingly expect financial institutions, fintechs, and agencies to support consumer education as part of responsible innovation.
Organizations such as Big Life Financial illustrate how this can be done in practice. By combining advisory services with practical, experience-based education, they help families and youth engage with money in ways that build durable skills, rather than just short-term knowledge. Businesses can partner with providers like Big Life Financial to design programs that are both impactful and operationally feasible.
1. Allowing Children to Make Financial Mistakes Safely
A central principle of effective financial responsibility training is that mistakes are not failures; they are data. Yet many adults instinctively shield children from any negative financial outcome. While well-intentioned, this protection often deprives young people of the very experiences that would teach them to be careful, thoughtful, and resilient with money later on. Businesses and agencies can model a different approach by intentionally designing “safe-to-fail” environments in their youth programs and community initiatives.
Safe financial mistakes are those that are small enough to absorb but meaningful enough to feel. For example, a teen who spends an entire monthly stipend on entertainment in the first week quickly experiences the discomfort of having nothing left for the rest of the month. This is far less damaging than maxing out a credit card as a young adult, yet it delivers a powerful lesson about planning, priorities, and self-control. The key is that the environment is structured, the amounts are limited, and there is guidance afterward to help the young person reflect and adjust.
📌 Key Takeaway: Avoid removing all financial discomfort from a young person’s life. Instead, ensure that the discomfort is small, temporary, and accompanied by constructive conversation.
Businesses can embed this philosophy into youth internship stipends, project budgets, or student-run initiatives. Agencies can apply the same principle in grant-funded programs, youth entrepreneurship challenges, or school partnerships. The objective is not to engineer perfect decisions, but to create a sequence of real decisions, real consequences, and real learning—under a protective ceiling that prevents serious harm.
2. Small-Scale Failure vs. Large-Scale Failure: A Risk Management Lens
Organizations are familiar with risk management frameworks: identify, quantify, mitigate, and monitor risk. The same logic applies to teaching financial responsibility. The question is not whether young people will fail at some point with money—they inevitably will—but when, how big, and with what support. From a risk perspective, it is far better for them to experience many small-scale failures early than a few catastrophic failures later in life.
Small-scale failure might look like overspending a summer job paycheck, underpricing a product in a school business fair, or forgetting to track a minor subscription cost. These events sting, but they are reversible. They also create a feedback loop that encourages better money management practices: tracking expenses, setting goals, or building a basic budget. By contrast, large-scale failure—such as taking on unmanageable student debt, defaulting on a loan, or entering a predatory contract—can have consequences that last for years or even decades.
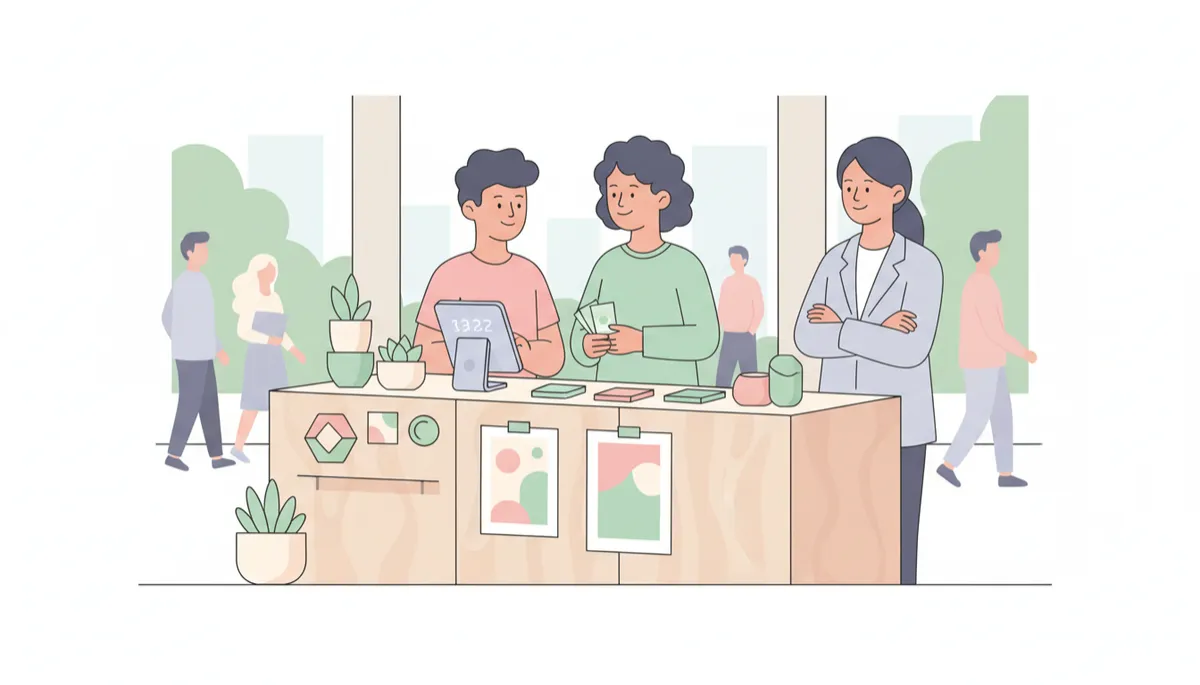
Structured micro-business projects help youth learn from small mistakes before real stakes are high.
Businesses and agencies can intentionally design for small-scale failure by capping exposure and clarifying boundaries. For example:
Setting a fixed, modest budget for a youth-led marketing experiment and allowing participants to choose how to allocate it, even if some decisions do not perform well.
Providing a limited inventory of low-cost products for a student-run pop-up and letting them test pricing, discounts, and promotions, knowing that unsold items are an acceptable cost of learning.
Offering a controlled digital wallet or prepaid card with clear parameters, so teens can practice digital money management without the risk of overdrafts or long-term debt.
In each case, the organization is effectively underwriting the learning process. Just as companies budget for R&D or pilot projects, they can budget for small, intentional losses that yield significant gains in youth financial responsibility and capability. Partners like Big Life Financial can help design these frameworks so that risk remains controlled while learning remains authentic.
3. Giving Responsibility Early Through Jobs and Business Tasks
Financial responsibility is not just about knowing how to spend; it is fundamentally connected to understanding how money is earned. When children and teenagers engage in real work—however simple—they gain a more grounded sense of value, effort, and exchange. For businesses and agencies, this creates a powerful avenue to combine workforce development with financial education by offering age-appropriate jobs and business-related tasks that include explicit money management components.
Early responsibility can take many forms, depending on the organization’s context and regulatory environment. Examples include:
Junior internships: Short-term roles where teens assist with basic administrative tasks, event support, or digital content, and receive a modest stipend they must plan and track.
Project-based assignments: Youth teams responsible for a discrete project—such as organizing a community event or running a social media campaign—with a defined budget and clear financial objectives.
Micro-entrepreneurship programs: Structured initiatives where participants develop a simple product or service, set prices, handle transactions, and reconcile basic income and expenses.
💡 Pro Tip for Organizations: Tie every youth role or project to at least one concrete financial metric—revenue, cost, margin, or budget variance—so participants see the direct link between their actions and money outcomes.
These experiences do more than teach arithmetic. They build a mindset of ownership and accountability. When a young person sees that arriving late to a shift affects service quality, which affects customer satisfaction, which ultimately affects revenue, they begin to understand financial responsibility at a systems level. When they participate in pricing discussions or decide whether to reinvest profits in marketing or withdraw them as earnings, they experience trade-offs that are central to sound money management and business thinking.
Big Life Financial and similar organizations often support businesses in structuring these opportunities. They help design roles, define learning outcomes, and provide simple tools—such as starter budgets, reflection templates, and debrief guides—that turn everyday tasks into deliberate financial education moments. For agencies managing public or philanthropic funds, such partnerships can ensure that youth employment programs deliver both income and lasting financial competence.
4. Building Competence Through Real Experience, Not Just Curriculum
Curriculum has an important role in financial education, but competence is built primarily through repeated, real experience. Just as no one becomes a confident driver by reading only a manual, no young person becomes financially responsible by memorizing terms like “interest rate” or “compound growth” in isolation. Competence emerges when theory meets practice—when a concept explained in a workshop is immediately applied to a real decision about saving, spending, or investing a small amount of money.
For businesses and agencies, this means designing programs around a cycle of learn–do–reflect:
Learn: Introduce a focused concept, such as budgeting, opportunity cost, or simple profit and loss, in concise, accessible terms.
Do: Immediately apply that concept to a real situation—planning how to allocate a stipend, deciding whether to purchase a tool for a project, or evaluating the results of a promotional discount.
Reflect: Facilitate a debrief where participants review what happened, what worked, what did not, and how they would adjust their money management strategies going forward.
Over time, this cycle develops not only technical skills but also confidence and judgment. Young people begin to see patterns: that impulse purchases often displace more meaningful goals, that tracking income and expenses reduces anxiety, and that small, consistent savings can create options they did not previously have. This is the essence of financial responsibility—aligning daily decisions with longer-term priorities and understanding the consequences of those decisions in concrete terms.
Designing Controlled Exposure to Money: Practical Models for Organizations
To translate these principles into action, businesses and agencies can adopt several practical models of controlled exposure to money. Each model can be tailored by age group, regulatory context, and organizational capacity, but they share a common goal: to give young people real financial responsibility within clear, protective boundaries.
Stipend-Based Learning Programs
In stipend-based models, participants receive a predictable, modest payment tied to program participation, projects, or internships. Instead of simply disbursing funds, organizations integrate guided money management activities:
Setting simple monthly budgets together at the start of the program.
Encouraging participants to allocate a portion for savings, a portion for discretionary spending, and a portion for a personal goal or investment in their own skills.
Reviewing outcomes at the end of each cycle—without judgment, but with honest discussion about what worked and what did not.
This approach aligns especially well with partners like Big Life Financial, who can supply frameworks and tools for tracking, reflection, and coaching. The emphasis is not on how much money is given, but on how thoughtfully it is used as a learning instrument.
Youth-Run Micro Ventures Within Corporate or Agency Settings
Another powerful model is the youth-run micro venture, hosted within a corporate lobby, community center, or agency facility. Here, small teams of young people design and operate a simple business—such as a snack stand, branded merchandise booth, or service kiosk—under the organization’s umbrella. The host provides space, basic infrastructure, and guardrails; youth handle pricing, selling, customer interaction, and basic bookkeeping.
These ventures naturally surface lessons about cash flow, cost of goods, profit margins, and customer behavior. They also make financial responsibility tangible: misplacing cash, over-ordering inventory, or misjudging demand all carry consequences that are visible and immediate, yet still small-scale. With proper mentorship and debrief sessions, each of these experiences becomes a case study in practical money management.
Digital Money Management Sandboxes
As financial services become more digital, it is essential to include online and card-based experiences in youth programs. Organizations can collaborate with financial partners to provide prepaid cards, controlled digital wallets, or simulated online banking environments. Within these sandboxes, participants can practice:
Tracking transactions in real time and categorizing spending.
Setting spending limits and alerts, then observing how their behavior aligns with those limits.
Experiencing the difference between planned recurring payments and impulsive one-off purchases.
Big Life Financial and similar providers can help ensure that these tools are not only technically sound but also pedagogically effective, embedding prompts, checkpoints, and educational content directly into the digital experience.
Aligning Stakeholders: Parents, Schools, Businesses, and Agencies
For controlled exposure to money to be truly effective, it should not exist in isolation. The most impactful initiatives align parents or guardians, schools, businesses, and agencies around shared goals and consistent messages about financial responsibility. Each stakeholder brings a different strength:
Parents and guardians provide daily context, reinforce habits at home, and model attitudes toward money, work, and risk.
Schools offer structured time, peer groups, and curricular connections to math, economics, and life skills education.
Businesses contribute real economic environments, meaningful work, and exposure to authentic financial decisions and trade-offs.
Agencies and nonprofits help coordinate, fund, and evaluate programs, ensuring equitable access and long-term sustainability.
Organizations like Big Life Financial can serve as integrators, helping align these stakeholders around a coherent strategy. By providing frameworks, training, and advisory support, they enable businesses and agencies to implement controlled exposure programs that are both responsible and scalable, while also respecting family values and educational standards.
Measuring Impact: From Anecdotes to Data-Driven Outcomes
Professional organizations naturally want to understand the return on investment of any initiative. Financial responsibility programs are no exception. While personal stories and testimonials are valuable, businesses and agencies should also define and track clear metrics to evaluate the effectiveness of controlled exposure to money. Potential indicators include:
Changes in participants’ ability to create and follow a simple budget over time.
Growth in savings balances or reductions in unplanned spending within program parameters.
Increased confidence in discussing money, asking questions, and making financial decisions.
Longitudinal outcomes, such as reduced reliance on high-cost credit or improved educational and career choices related to financial literacy.
Data does not have to be complex to be useful. Simple pre- and post-program surveys, spending logs, and reflection journals can provide meaningful insights. Experienced partners can help design measurement strategies that respect privacy, minimize administrative burden, and still deliver actionable information for continuous improvement.
The Role of Big Life Financial in Supporting Organizational Efforts
Implementing controlled exposure to money, managing risk appropriately, and aligning multiple stakeholders can be complex. This is where specialized partners such as Big Life Financial can add significant value. They bring expertise in both technical money management and human behavior, helping organizations design programs that are practical, engaging, and sustainable.
Big Life Financial can assist with:
Structuring safe-to-fail financial experiences, including guidelines for small-scale exposure and clear escalation pathways if issues arise.
Developing age-appropriate curricula that are tightly integrated with real-world activities, rather than detached classroom content.
Training mentors, managers, and program staff to facilitate reflective conversations about money, decisions, and consequences without shaming or lecturing participants.
Designing measurement and reporting frameworks that allow organizations to demonstrate impact to boards, funders, and regulators.
By leveraging this kind of expertise, businesses and agencies can move quickly from good intentions to effective implementation, ensuring that their investments in youth financial responsibility lead to lasting change for participants and tangible value for the organization.
Turning Today’s Small Lessons into Tomorrow’s Big Outcomes
The next generation will navigate a financial landscape that is more complex, more digital, and more fast-moving than any before it. Credit, subscriptions, digital wallets, and investment products are increasingly accessible at younger ages. Against this backdrop, businesses and agencies have a critical choice: either allow young people to encounter money haphazardly, or intentionally guide them through controlled exposure that builds real financial responsibility and money management competence over time.
Allowing children and teens to make financial mistakes safely is not a risk to be avoided; it is a strategy to be embraced. When organizations distinguish small-scale failure from large-scale failure and design programs that keep consequences manageable, they transform missteps into powerful learning events. When they provide early responsibility through jobs and business tasks, they connect earning and spending in a way that makes money real. And when they prioritize real experience over abstract curriculum, they help young people move from knowledge to competence—and ultimately, to confidence.
For businesses and agencies, this is more than a corporate social responsibility initiative. It is an investment in the financial health of future employees, customers, and citizens. With thoughtful design, cross-sector collaboration, and support from specialized partners like Big Life Financial, organizations can play a decisive role in shaping how the next generation understands and manages money. The stakes are high, but so is the potential upside: a society in which more young adults enter life prepared, resilient, and equipped to make sound financial decisions—not because they were shielded from money, but because they learned to handle it, one controlled experience at a time.
Sometimes, hearing an idea explained in conversation makes it click in a different way. Take a moment to watch the video and explore more of the thoughts and experiences behind this topic.
