Take Control of Your Financial Future Today
Financial Ownership, Financial Planning, Collaborating With Advisors, Investment Strategy
Taking Ownership of Your Financial Future
Your money touches every part of your life—from where you live and how you work, to the choices you can make for your family and your future. Taking true financial ownership means moving from a passive, “I hope it works out” mindset to becoming an informed, engaged decision-maker. It is not about doing everything alone; it is about understanding enough to ask better questions, make confident choices, and collaborate effectively with the professionals who support you.
What It Really Means to Take Financial Ownership
Taking ownership of your financial future is not a single decision; it is an ongoing practice. It means you:
Understand where you are financially—your income, spending, debt, assets, and obligations—in clear, simple terms.
Set goals that reflect what matters most to you, not just generic benchmarks or rules of thumb.
Participate actively in your financial planning and investment strategy instead of outsourcing every decision without understanding it.
Build relationships with professionals—planners, advisors, tax experts—where you are a partner, not a bystander.
At BLF, we often describe financial ownership as the shift from “What should I do?” to “Help me understand my options so I can decide.” That subtle change in language reflects a powerful change in mindset: your advisor is there to guide and inform, but the decisions are ultimately yours.
Step 1: Become an Active Participant in Your Planning
Many people meet with an advisor once a year, nod through the meeting, sign the paperwork, and then file the statements away. That is not financial ownership —that is delegation without understanding. To become an active participant in your financial planning , you do not need a finance degree; you need curiosity, clarity, and a willingness to engage.
Start With Your “Why,” Not Just the Numbers
Before you talk about portfolios or products, get clear on what you are planning for. Ask yourself:
What kind of life do I want in 5, 10, or 20 years?
What do I want to be able to say “yes” to—travel, career changes, supporting family, giving back?
What do I want to protect myself and my loved ones from—unexpected health events, job loss, market downturns?
A strong investment strategy is simply a tool to support those answers. When you walk into a meeting with your “why” in mind, you can evaluate every recommendation through a simple lens: “Does this move me closer to or further from the life I want?”
Prepare for Every Planning Conversation
Active participation begins before you sit down with an advisor. Before each review meeting, take 20–30 minutes to prepare:
Review your most recent statements and note anything you do not understand (fees, holdings, performance numbers).
List any major changes in your life: job moves, new family members, health shifts, large purchases, or new goals.
Write down specific questions you want answered: “How risky is my current investment strategy ?” “What would happen to my plan if I retired three years earlier?” “How are taxes being managed?”
💡 Pro Tip: Treat planning meetings like medical appointments: arrive with notes, share symptoms (your concerns), and ask for clear explanations before agreeing to any treatment.
Ask for Plain Language and Visuals
An engaged client is not the one who nods along; it is the one who says, “I do not follow that—could you explain it another way?” When your advisor describes a financial planning recommendation or an investment strategy , ask for:
A simple summary in one or two sentences.
A visual—such as a chart or projection—showing how the change impacts your long-term plan.
The trade-offs: what you gain, what you give up, and what could go wrong.
At BLF, we often use color-coded projections in BLF Mint and BLF Teal to show “on track,” “caution,” and “off track” scenarios. You do not need to memorize every data point; you just need to understand the story the numbers are telling about your future.
Step 2: Understand Your Financial Situation Deeply
You cannot own your financial future if you do not know where you stand today. A deep understanding does not mean tracking every penny obsessively; it means having a clear, accurate picture of your financial life and how the pieces fit together. Think of it as your personal financial dashboard: simple, up to date, and meaningful at a glance.
Map Your Current Reality: Assets, Debts, Income, and Spending
Start by gathering the basics. Create a simple one-page snapshot that includes:
Assets: Cash, savings, investments, retirement accounts, property, and any business interests.
Debts: Mortgages, student loans, credit cards, personal loans, and any other obligations.
Income: Salary, bonuses, business income, rental income, and any side income streams.
Spending: Essential expenses (housing, food, utilities, insurance) and lifestyle spending (travel, dining, hobbies).
This is your financial “starting line.” Many BLF clients are surprised by how empowering it feels just to see everything in one place. It removes the vague anxiety of “I should be doing more” and replaces it with concrete information you can act on.
Know Your Cash Flow—Not Just Your Balance
Deep understanding means looking beyond account balances to how money moves through your life each month. Ask yourself:
How much flows in, after taxes and deductions?
How much flows out, on average, to fixed and variable expenses?
How much is consistently being saved or invested toward your goals?
Even a simple three-category view—“must pay,” “nice to have,” “future me”—can transform how you think about money. When you see how much is actually going toward “future me,” it becomes easier to adjust your financial planning and make deliberate trade-offs instead of accidental ones.
Understand Your Investment Strategy in Plain Terms
You do not need to become a professional investor, but if you have money in the market, you should be able to answer a few basic questions about your investment strategy :
What am I invested in, broadly—stocks, bonds, cash, real estate, alternatives?
Why is this mix appropriate for my age, goals, and comfort with risk?
How much could my portfolio reasonably go up or down in a typical year—and in a bad year?
What am I paying in fees, and to whom?
If you cannot answer these today, that is not a failure—it is an opportunity. Bring these questions to your next meeting. A key part of financial ownership is insisting that your investment strategy be something you can explain to a friend in a few sentences, not a black box you simply hope will work.
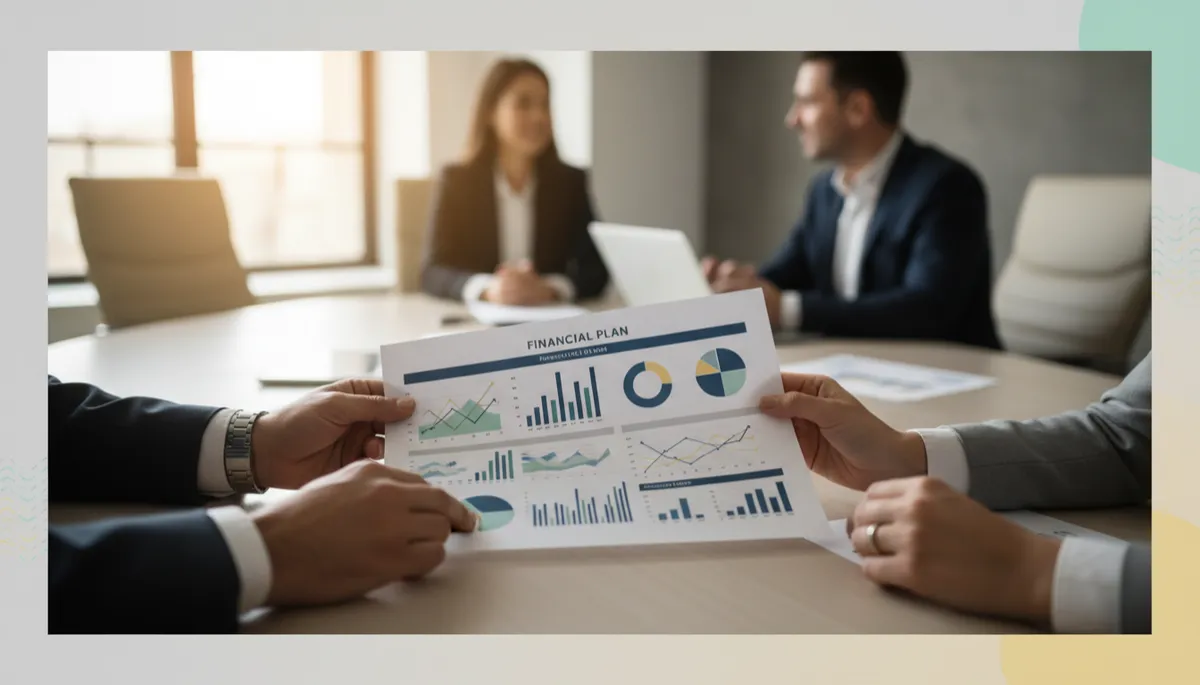
A clear snapshot of assets, debts, and goals turns vague worry into focused action.
Step 3: Collaborating Effectively With Advisors
The goal is not to go it alone. The goal is to build a team around you—and to be the leader of that team. That is the heart of collaborating with advisors . A great advisor relationship feels like a partnership, where your values drive the plan and your advisor brings expertise, structure, and accountability.
Choose Advisors Who Welcome Your Questions
Not all advisors work the same way. When selecting someone to guide your financial planning and investment strategy , look for signs that they value your engagement:
They ask about your life, not just your assets—your values, fears, and priorities.
They explain their recommendations in clear language and are patient with follow-up questions.
They welcome your input and do not pressure you into quick decisions or complex products you do not understand.
At BLF, we see ourselves as guides and educators as much as planners. A client who leaves a meeting feeling more confident and informed—even if they choose to move slowly—is a success story, because it means they are truly taking financial ownership .
Set Expectations and Roles Clearly
Effective collaborating with advisors starts with clarity. In your early conversations, ask:
What exactly will you handle, and what will remain my responsibility?
How often will we meet or check in, and what should I bring to those meetings?
How do you prefer to communicate between meetings—email, phone, secure portal—and how quickly do you typically respond?
When everyone knows their role, collaboration becomes smoother. For instance, your advisor might monitor your investment strategy and rebalance as needed, while you commit to updating them whenever your income, family situation, or goals change. Together, you keep the plan alive and relevant.
Use Meetings to Make Decisions, Not Just Receive Reports
Many review meetings turn into one-way presentations: charts, updates, and jargon. To truly collaborate with advisors , reshape those meetings into decision sessions. Before each meeting, ask your advisor:
What decisions do we need to make together this time?
What are the top three things I should focus on over the next 12 months?
Then, during the meeting, pause after each recommendation and summarize it in your own words: “So, if I understand correctly, you are suggesting we shift part of my portfolio to reduce risk as I get closer to retirement, which may mean slightly lower expected returns but smoother ups and downs. Is that right?” This simple habit ensures you are not just hearing the plan—you are owning it.
Turning Insight Into Action: Building Your Ownership Roadmap
Knowledge without action does not change your future. To make financial ownership real, create a simple roadmap for the next 12 months—one that blends your role with the support of your advisor team. Here is a framework you can adapt with your BLF planner or any trusted professional.
1. Clarify Your Top Three Goals
Choose no more than three primary goals for the next one to five years. For example:
Build a six-month emergency fund within two years.
Increase retirement contributions to 15% of income over the next 18 months.
Pay off high-interest debt and redirect those payments into investments.
Share these goals with your advisor and ask how your current financial planning and investment strategy can be aligned—or realigned—to support them.
2. Create Simple Habits That Support Your Plan
Ownership is built in small, repeatable actions, not grand gestures. Consider habits like:
A 15-minute “money check-in” once a week to glance at accounts and upcoming bills.
Automatic transfers to savings or investment accounts on payday, so your goals are funded before lifestyle spending kicks in.
A quarterly review with your advisor to revisit your investment strategy , check progress, and adjust for any life changes.
These habits compound over time, just like your investments. They keep you connected to your plan without requiring constant attention.
3. Build a Feedback Loop With Your Advisor
Collaboration works best when it is continuous, not just annual. With your advisor, design a simple feedback loop:
You commit to sharing updates when big life events happen—career changes, major purchases, new family responsibilities.
Your advisor commits to reaching out when market conditions or new opportunities suggest a review of your investment strategy .
Together, you agree on what “success” looks like each year—not just investment returns, but progress toward your life goals.
📌 Key Takeaway: When you and your advisor both know what you are working toward and how you will measure it, every conversation becomes more focused and productive.
Your Future, Your Decisions, Your Team
Taking ownership of your financial future does not mean having all the answers. It means being willing to ask better questions, to understand your situation deeply, and to work alongside professionals who respect your role in every decision. It is about shifting from “I hope I am okay” to “I know where I stand, I know where I am headed, and I know who is helping me get there.”
When you become an active participant in your financial planning , you stop drifting and start steering. When you understand your finances clearly, you replace vague anxiety with informed confidence. And when you are collaborating with advisors as a true partner, your investment strategy and your life strategy finally line up.
Whether you are just getting started or refining an existing plan, the most important step is the one you take next: opening your statements instead of ignoring them, scheduling that planning conversation instead of postponing it, or writing down your questions instead of assuming you should already know the answers. Those are the moments where financial ownership is born.
Your financial future will not be shaped by markets alone. It will be shaped by your choices—how engaged you are, how clearly you see your situation, and how intentionally you build and lead the team around you. With the right mindset, the right information, and the right partners, you can turn money from a source of stress into a tool for building the life you want.
You’ve reached the end of the article, but that doesn’t have to mean the end of the conversation. Press play and explore more of the ideas behind this piece, along with perspectives that can give you something new to consider.
