
Q4 Tax Strategies: What Your CPA Won’t Tell You
Tax Strategy, Q4 Tax Strategies, Year-end Planning, Tax Reduction
Q4 Tax Strategies for Business Owners: What Your CPA Won’t Tell You
As a senior software engineer who’s spent too many late Q4 nights refactoring both code and cap tables, I’ve learned this: tax strategy is just another system design problem. The difference is that most business owners ship their “tax architecture” once a year, blindly, by letting a reactive CPA file whatever the numbers say—rather than deliberately engineering the outcome. Q4 is when that architecture is either optimized… or permanently locked in until next year.
Why Q4 Is the Production Environment for Your Tax Strategy
Think of the year as a development cycle. Q1 through Q3 are your sprints. Q4 is when the code freeze hits, and whatever you’ve deployed is what goes to production on December 31. That’s why Q4 Tax Strategies matter more than any other quarter: it’s the last window where you can still change the behavior of the system before the tax year closes.
Once the calendar flips, your options shrink dramatically. You can still do some things—like certain retirement plan contributions—but most of the powerful Tax Reduction levers are time-bound to actions taken before year-end. That’s why serious businesses treat Year-end Planning as a project, not an afterthought. You wouldn’t ship a major release without a staging environment and a deployment plan; your tax position deserves the same discipline.
📌 Key Takeaway: Q4 is not about guessing your tax bill; it’s about deliberately shaping it while you still have write-access to the year.
The Reactive CPA Problem: Filing vs. Architecting
Most CPAs operate like log parsers, not system architects. They take what already happened, normalize it into the right format, and submit it to the IRS API. That’s filing, not architecting. It’s the equivalent of a developer who only runs npm test after the code has already been deployed and users are complaining in production.
An architecting mindset asks different questions:
What entity structure produces the best long-term tax behavior for this business model?
Which Q4 Tax Strategies are still available this year, and what needs to be executed before December 31 to capture them?
How do tax, investments, and insurance coordinate so that every dollar has a defined job and lifecycle?
Filing is retrospective. Architecting is proactive. If all you get from your CPA is a once-a-year “here’s what you owe” email, you’re effectively running a monolith with no observability and hoping it scales. That’s not strategy; that’s wishful thinking with a K-1 attached.
💡 Pro Tip: Ask your CPA, “What are the top three moves we can still make this Q4 to change our tax outcome?” If the answer is silence or “it’s too late,” you don’t have an architect—you have a historian.
Five Q4 Moves That Actually Change the Math
Let’s walk through five Q4 Tax Strategies that go beyond “buy a truck” and actually behave like well-designed components in your financial architecture: accelerated deductions, entity election changes, R&D credit capture, retirement plan contributions, and charitable structures. For each, I’ll frame it the way an engineer thinks—inputs, outputs, and constraints—and show how you might even model it in code to make decisions instead of guesses.
1. Accelerated Deductions: Pulling Expenses Forward on Purpose
Accelerated deductions are about time-shifting: taking expenses you know you’ll incur next year and legitimately pulling them into this year to reduce taxable income. Think prepaid software, marketing retainers, equipment, or professional fees. It’s not magic; it’s scheduling. From an engineering perspective, you’re moving cost recognition earlier in the timeline to change the shape of your cash and tax flows. The constraints are key: the expense must be ordinary, necessary, and actually tied to a real business need. But if you’re already going to spend the money in Q1, Q4 is your last chance to pull that deduction into the current year and intentionally shape your Year-end Planning outcome.
2. Entity Election Changes: Choosing the Runtime for Your Income
Your entity type—LLC, S-corp, C-corp, partnership—is like your application runtime. It determines how income flows, how it’s taxed, and what optimizations are available. Too many businesses stay on the default runtime they started with, even after their traffic (revenue) and architecture (ownership, profit margins) have changed dramatically. Q4 is when you should be evaluating whether an entity election change, often effective for the current year if timed correctly, would materially reduce your tax load.
For example, moving from a default LLC taxation to an S-corp election can allow you to split income between salary and distributions, potentially reducing self-employment tax. It’s not always the right answer, but it’s a lever that should be modeled—not ignored. You can even sketch a simple comparison in code to inform the conversation with your CPA.
Entity election changes are a classic “what your CPA won’t tell you” moment—often because they require more planning, more explanation, and more liability on their side. But for growing businesses and agencies, this can be one of the most powerful Q4 Tax Strategies to re-architect your long-term tax behavior.
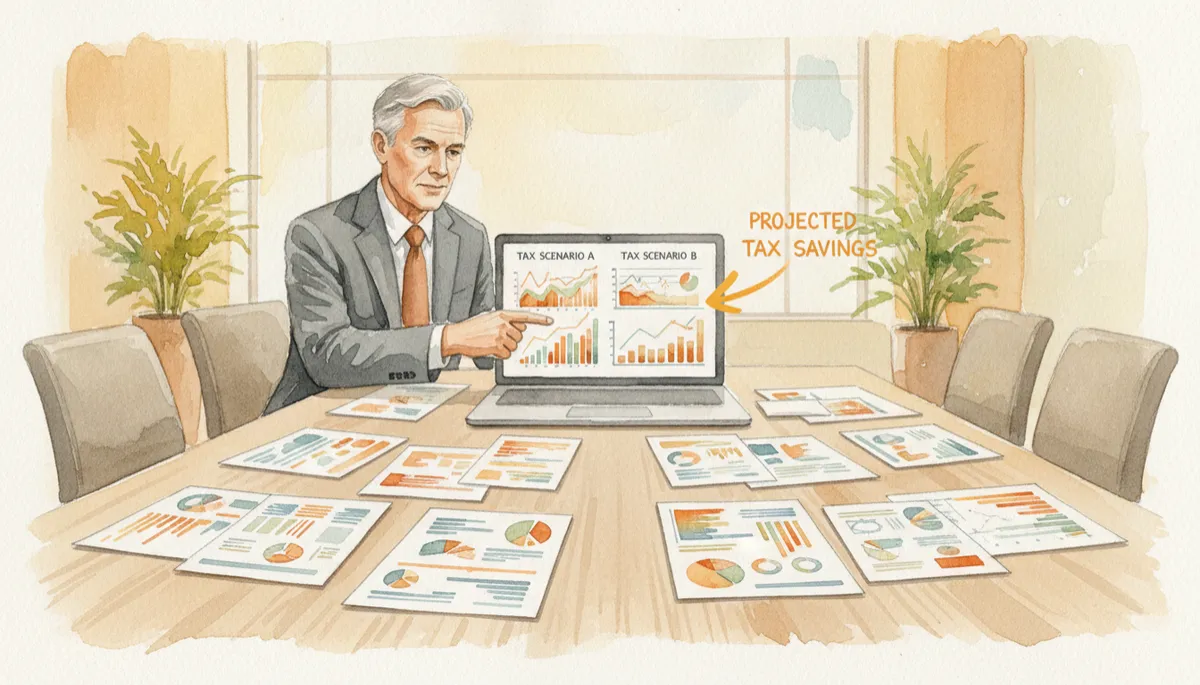
Modeling entity options in Q4 often reveals five- and six-figure savings.
3. R&D Credit Capture: Getting Paid for Solving Hard Problems
If you run a software product company or a technical agency and you’re not at least exploring the R&D tax credit, you’re leaving serious money on the table. The R&D credit is essentially the IRS acknowledging that building new systems, features, and architectures is hard—and they’re willing to subsidize that effort if you document it correctly. This is not just for labs in white coats; it often applies to the work your dev team is already doing.
Q4 is when you still have time to:
Identify qualifying projects (new features, performance improvements, system redesigns).
Map developer, QA, and architect hours to those projects.
Coordinate with a tax professional who actually understands software R&D.
The real calculation is more nuanced, but the point is simple: you can and should treat R&D credit capture as part of your Year-end Planning. If you’re already paying engineers to push the envelope, Q4 is your last chance to make sure that work is tagged, documented, and monetized via the credit.
4. Retirement Plan Contributions: Turning Tax into Future Optionality
Retirement plans are one of the few tools that can still affect your tax bill even after December 31, depending on the structure. But the decision to use them—and at what scale—is a Q4 conversation. Solo 401(k)s, SEP IRAs, and defined benefit plans all let you convert current taxable income into long-term invested capital, often with significant Tax Reduction in the current year.
For business owners and agency principals, the right plan design can allow very large contributions—well beyond what a typical employee 401(k) can handle. From an engineering lens, you’re trading one variable (current tax) for another (future flexibility and investment growth), and Q4 is when you decide how aggressively to flip that switch.
The nuance comes from coordinating this with your cash flow, your investment strategy, and your exit plans. Overfunding a retirement plan that doesn’t match your long-term goals is like over-optimizing a microservice nobody uses. Q4 is when you zoom out and decide how retirement contributions fit into the broader system design, not just this year’s tax bill.
5. Charitable Structures: Donor-Advised Funds and Gifting as Strategy
Traditional advice says, “Give to charity, get a deduction.” That’s fine, but it’s like hard-coding values instead of using configuration. Q4 is when you can design charitable structures—like donor-advised funds (DAFs) or charitable LLCs—that decouple when you give for tax purposes from when the funds actually reach the end charities. That gives you more control over both impact and timing.
A DAF, for example, lets you make a large contribution in a high-income year, get the deduction now, and then grant the money out over time. For business owners with volatile income—big exit year, unusually profitable Q4, or a one-time deal—this is one of the most powerful Q4 Tax Strategies available.
The catch: these structures must be set up and funded by year-end for the deduction to count this year. That’s why Q4 is not the time to casually “see what’s left over” for giving; it’s when you intentionally decide whether charitable structures are part of your long-term architecture or just a random feature toggle.
Why Coordination Between Tax, Investment, and Insurance Changes Everything
In software, you’ve probably seen what happens when teams ship independently with no integration tests. Things compile, but the system fails at the seams. Most business owners are running that exact anti-pattern with their money: tax, investments, and insurance are three separate repos with no shared architecture or CI pipeline. Q4 is when those seams either hold—or split under load.
Tax decides how much of each dollar you keep.
Investment decides how fast those kept dollars grow and how volatile that path is.
Insurance decides what happens when the unexpected hits—lawsuits, disability, death, or a key partner exiting.
When these are coordinated, every Q4 move you make is evaluated across all three domains. For example:
A retirement plan contribution isn’t just a tax play; it’s mapped to your investment allocation and your eventual exit strategy from the business.
An entity election change is checked against liability protection and the need for umbrella or key-person coverage.
A charitable structure is evaluated not just for this year’s deduction, but for how it fits into your long-term portfolio and legacy.
This is obviously oversimplified, but it reflects the mindset: each move has multi-dimensional impact. Coordinated advisors—tax, investment, and insurance—act like a cross-functional architecture review, not three separate teams shipping conflicting features. Q4 is when that coordination matters most, because the window to act is closing and the stakes are highest.
📌 Key Takeaway: If your tax pro, investment advisor, and insurance specialist have never been on the same call, you don’t have a strategy—you have disconnected services hoping the network holds.
Making Q4 Tax Strategies a Standard Part of Your Annual Release Cycle
The businesses and agencies that consistently win on taxes don’t have secret loopholes; they have a repeatable Q4 process. They treat Year-end Planning like a major release with clear milestones:
Early Q4: Run projections with your CPA and internal team. Where will taxable income likely land if nothing changes?
Mid Q4: Evaluate the five core Q4 moves—accelerated deductions, entity election changes, R&D credit capture, retirement plan contributions, and charitable structures—through the lens of your specific numbers and goals.
Late Q4: Execute the chosen moves with coordinated input from tax, investment, and insurance advisors. Confirm documentation and deadlines so nothing falls through the cracks.
Over time, this becomes muscle memory. You stop being surprised by your tax bill in March because you already engineered it in November. Your CPA stops being a once-a-year inbox notification and becomes part of a small, aligned architecture team. And your business stops leaking capital to taxes simply because no one bothered to refactor the financial codebase.
Next Step: Schedule Your Q4 Strategy Session
If you’re a business owner or agency lead who thinks in systems, you already know that hoping for a better outcome without changing the architecture is wishful thinking. The same rules apply to your taxes. Q4 is your last, best chance each year to refactor how money flows through your business before the year-end code freeze hits on December 31.
You don’t need another generic “buy some equipment” tip. You need a deliberate, engineered set of Q4 Tax Strategies that align accelerated deductions, entity election changes, R&D credit capture, retirement plan contributions, and charitable structures into one coherent plan—coordinated across tax, investment, and insurance so every move is pulling in the same direction.
If you’re ready to stop guessing and start architecting, schedule your Q4 strategy session. Bring your numbers, your goals, and your questions. We’ll treat your finances like the complex system they are—and help you design a tax outcome you’re not surprised by next spring.
