Maximize Wealth with Multi-Year Tax Strategy
Tax Strategy, Long-term Wealth Planning, Multi-year Tax Strategy
Stop Planning Taxes One Year at a Time: The Power of Multi-Year Strategy
Local businesses that think strategically about taxes over five, ten, or even twenty years often end up with dramatically more cash, stronger balance sheets, and a smoother path to long-term growth than those who only focus on “What do we owe this April?” This is the difference between reactive tax filing and proactive, strategic Long-term Wealth Planning.
The Planning Horizon: The Hidden Lever in Your Tax Strategy
Every business makes decisions with some kind of time frame in mind, whether they say it out loud or not. That time frame is your planning horizon—the period you’re looking ahead when you make financial and operational choices. For many local businesses, the effective planning horizon is twelve months or less. The focus is: this year’s revenue, this year’s expenses, this year’s tax bill.
High-level organizations, institutional investors, and sophisticated family offices operate differently. Their planning horizon stretches across multiple years, often decades. They ask questions like:
How will this decision affect our taxes over the next five to ten years?
Can we structure this investment to create deductions and credits across multiple tax years?
What is the long-term wealth impact, not just this year’s savings?
Your planning horizon matters because taxes are not a one-year game. Many of the most powerful opportunities—real estate strategies, depreciation timing, credits, retirement plans, and entity structures—play out over several years. When your horizon is too short, you only see the obvious, immediate moves. When you extend your horizon, you start to see sequences of decisions that compound into far greater savings and long-term wealth creation.
📌 Key Takeaway: Your tax results are a reflection of your planning horizon. Short horizon, small wins. Multi-year horizon, strategic gains.
Short-Term vs. Long-Term Tax Decisions: Why the Difference Is So Big
When you only plan taxes one year at a time, you naturally focus on what will reduce this year’s bill. That often means accelerating expenses, deferring income, or grabbing whatever deduction is easiest to implement before year-end. These tactics are not wrong—but they are incomplete. They can even backfire when they ignore the bigger picture of your Multi-year Tax Strategy and Long-term Wealth Planning goals.
The Limitations of Single-Year Tax Thinking
Consider a common year-end move: buying equipment you do not urgently need just to create a deduction this year. On paper, you save taxes. In reality, you may have:
Tied up cash that could have been used for marketing, hiring, or paying down high-interest debt
Shifted deductions you might need more in a future high-income year into a lower-income year where the benefit is smaller
Missed the chance to coordinate depreciation, financing, and credits into a unified, multi-year plan
Short-term decisions often chase immediate relief instead of aligning with where you want the business—and your personal wealth—to be in five or ten years. They can feel smart in the moment, but they may cost you far more in missed opportunities over time.
The Power of Long-Term Tax Positioning
Long-term tax decisions start with a different question: “How do we position this business and our personal finances so that, over many years, we legally minimize taxes and maximize after-tax wealth?” That strategic mindset considers:
Expected revenue and profit growth over several years, not just this year’s numbers
Planned real estate acquisitions, equipment upgrades, or expansion projects and how they interact with depreciation and financing
Future exit plans, succession, or sale of the business—and the tax consequences of each path
Personal wealth goals, including retirement, real estate portfolios, and tax-efficient investing
The result is a coordinated Multi-year Tax Strategy that deliberately sequences moves to take advantage of changing income levels, evolving tax laws, and compounding growth. It is not about a single “big deduction”; it is about designing a long-term path where taxes consistently take less from every dollar you earn and invest.
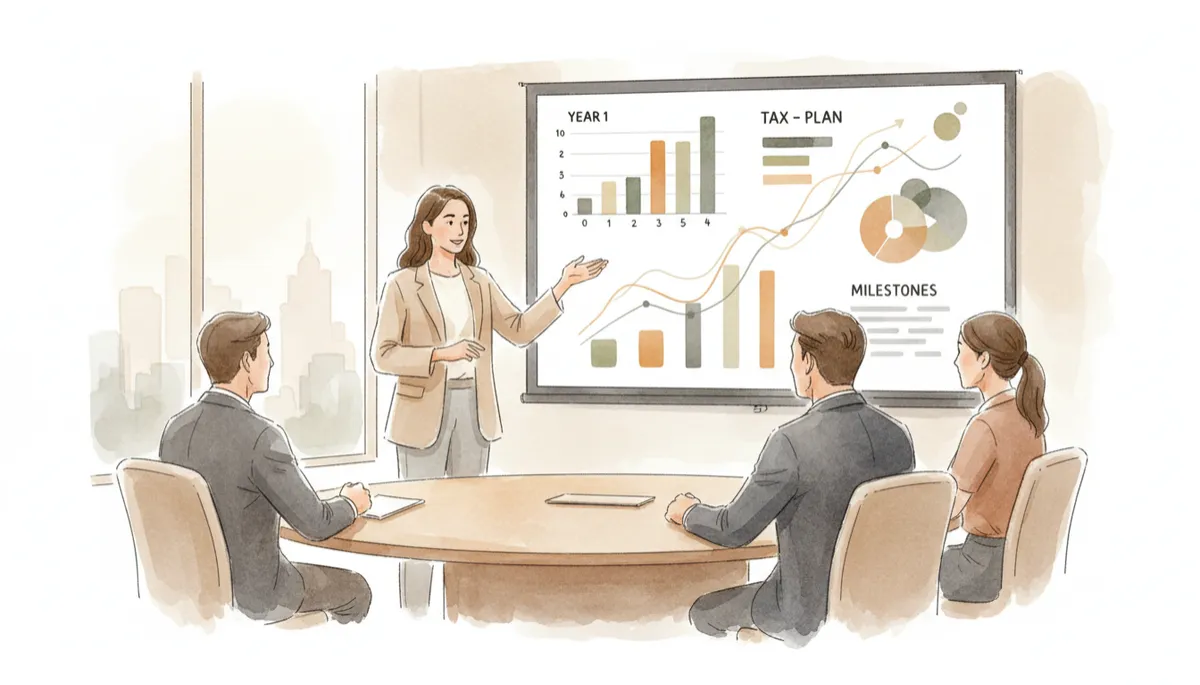
Multi-year tax mapping turns scattered decisions into an intentional path to wealth.
Real Estate: A Classic Example of Multi-Year Tax Strategy in Action
Real estate is one of the clearest illustrations of why a multi-year planning horizon matters. A property purchase is rarely about this year’s taxes. It is about years of depreciation, the timing of capital gains, and how the property fits into your broader Long-term Wealth Planning strategy as a business owner.
Example: Buying a Building for Your Business
Imagine a local business that currently rents space but is considering buying a building. A one-year tax mindset might only ask, “How much can we deduct this year if we buy?” A multi-year mindset asks:
Over the next 5–10 years, how will depreciation deductions from the building offset rising business income?
Can we structure the ownership (for example, a separate entity that leases to the operating company) to optimize liability protection and tax efficiency?
Would cost segregation accelerate certain components’ depreciation, creating larger deductions in the years when income is expected to spike?
How does this property contribute to your personal wealth outside the business, including eventual sale or generational transfer?
When Big Life Financial works with business owners on decisions like this, the discussion is not just “buy vs. rent this year.” It is “What does owning this asset do for your tax exposure, cash flow, and net worth over the next decade and beyond?” That is Multi-year Tax Strategy thinking, and it is exactly how high-level investors evaluate real estate moves.
Coordinating Real Estate with Exit and Succession Plans
Real estate also becomes a strategic lever when you think about exiting your business or passing it to the next generation. A single-year tax view might only consider the gain or loss on a sale. A multi-year view looks at:
Whether to sell the business but keep the building, turning it into a long-term rental income stream with ongoing deductions
How to time the sale and use strategies such as installment sales or 1031 exchanges to manage capital gains over multiple years
How ownership should be structured to support estate planning, asset protection, and Long-term Wealth Planning for your family
These are not decisions you want to rush through in the year of sale. They are best designed years in advance, with a clear multi-year map that coordinates tax rules, financing, and your personal goals.
Depreciation: Turning a Compliance Rule into a Strategic Tool
Depreciation is often treated as a bookkeeping formality—something the accountant handles quietly in the background. But for strategic business owners, depreciation is a powerful lever in a Multi-year Tax Strategy. It determines when and how you recognize the cost of major assets over time, and that timing can dramatically affect your tax burden across multiple years.
Short-Term Depreciation Choices vs. Multi-Year Design
A one-year approach might push for the largest possible deduction right now—using bonus depreciation or Section 179 expensing whenever possible. Again, that can be beneficial, but it is not automatically the best move. A multi-year approach asks:
Are we in a relatively low-income year now, with higher profits expected in the next few years? If so, should we stretch some depreciation into those higher-tax years instead of using it all today?
Do we anticipate major credits or losses in certain years that will already reduce our tax bill, making additional deductions less valuable in those periods?
Can we align depreciation schedules with anticipated revenue cycles or expansion phases to smooth cash flow and tax payments?
High-level organizations routinely model depreciation across multiple years, treating it as a strategic resource rather than an afterthought. Local businesses can use the same mindset, especially when guided by advisors like Big Life Financial who understand both the tax code and the realities of small and mid-sized enterprises.
Tax Credits: Planning Ahead to Capture What Others Miss
Tax credits are some of the most valuable tools in the code because they reduce your tax bill dollar for dollar. Yet many local businesses miss out on them simply because they only think about taxes at filing time. By then, it is often too late to qualify or properly document the activities that would have earned the credit. This is another area where a Multi-year Tax Strategy pays off.
Strategic Use of Credits Over Multiple Years
Credits related to research and development, energy efficiency, hiring in certain zones, or training often require planning, documentation, and sometimes specific types of investments or activities. A one-year mindset asks, “Did we qualify for anything last year?” A multi-year mindset asks:
Over the next 3–5 years, what credits are realistically available to a business like ours, given our growth and investment plans?
How do we design projects—technology upgrades, process improvements, facility changes—so they align with those credit rules from day one?
What systems do we need to track and document qualifying activities in real time, so we do not lose credits due to missing paperwork?
By mapping credits into a Multi-year Tax Strategy, you turn them from occasional windfalls into a reliable part of your Long-term Wealth Planning. Big Life Financial often helps clients identify multi-year credit opportunities that more reactive tax preparers never surface, simply because they are looking ahead instead of backward.
How Multi-Year Planning Unlocks Bigger, Compounding Savings
The real power of multi-year tax planning is not just in any single tactic. It is in how multiple decisions, coordinated over time, create compounding savings and stronger after-tax cash flow. When your planning horizon extends beyond this year, you can:
Sequence Decisions for Maximum Impact
Think about your business like a chessboard. Each move changes what is possible in future moves. With a Multi-year Tax Strategy, you intentionally sequence:
When to buy or sell key assets, such as vehicles, equipment, or real estate, to align deductions and gains with income levels and credit opportunities
When to implement or expand retirement plans, ensuring contributions are made in years where they deliver the greatest overall benefit to owners and key employees
How to time income recognition, bonuses, or distributions to avoid bracket spikes and make use of lower-rate years where possible
When these decisions are made in isolation, you might get short-term wins. When they are coordinated across several years, they reinforce one another, often producing savings that are many times larger than any single tactic by itself.
Smooth Out Tax Volatility and Protect Cash Flow
Another advantage of multi-year planning is stability. Many business owners experience “tax surprises”—years where the bill is dramatically higher than expected, straining cash flow and forcing rushed decisions. With a strategic, forward-looking plan, you can anticipate those high-income years and prepare for them by:
Reserving cash in advance so the tax bill does not disrupt operations or growth investments
Lining up major deductions, credits, or strategic purchases in the same year to offset the spike in taxable income
Adjusting compensation, distributions, or entity structure ahead of time to smooth the tax impact
This is how high-level organizations maintain predictable, manageable tax outflows even as their revenues grow and fluctuate. Local businesses can adopt the same discipline by building a Multi-year Tax Strategy that is reviewed and updated regularly, not just once a year at filing time.
Thinking Like High-Level Organizations and Investors
The tax code is the same whether you are a local business or a multinational corporation. The difference is in how you approach it. High-level organizations and sophisticated investors do not wait for their accountants to tell them what happened last year. They proactively design strategies that align taxes with their long-term objectives. You can do the same, at a scale that fits your business.
Adopting a Strategic, Boardroom-Level Mindset
At the board level, tax planning is not a seasonal task; it is a standing agenda item. Decisions about capital allocation, financing, hiring, and expansion are all evaluated through a tax-aware lens. For your business, that means:
Reviewing your tax position mid-year and late in the year, not just after the year ends
Mapping out a 3–5 year view of expected profits, investments, and exits, and revisiting it annually
Treating tax planning as part of your Long-term Wealth Planning, not just a compliance cost
Big Life Financial specializes in helping local businesses think at this higher, more strategic level—without overwhelming owners with complexity. The goal is not to turn you into a tax technician; it is to give you a clear, multi-year roadmap and a team that can execute it with you.
Aligning Business Taxes with Personal Wealth Goals
High-net-worth investors never separate tax planning from wealth planning. They understand that every tax decision in the business eventually shows up in their personal balance sheet. As a local business owner, you have the same opportunity. A truly strategic Multi-year Tax Strategy connects:
How and when you take money out of the business (salary, distributions, dividends, rent, or interest)
How you build personal assets—real estate, tax-advantaged accounts, and diversified investments—using after-tax dollars efficiently
How your eventual exit from the business funds your retirement and legacy goals
When your business tax planning and personal Long-term Wealth Planning are aligned, every year becomes another step toward financial independence, not just another round of filing returns.
💡 Pro Tip: Ask your advisor to show you a 5–10 year projection that integrates business taxes, personal income, and investment growth. If they cannot, you may need a more strategic partner.
Putting Multi-Year Tax Strategy to Work in Your Local Business
Moving from one-year tax planning to a multi-year, strategic approach does not require you to overhaul everything overnight. It starts with a shift in mindset and a few practical steps that create immediate clarity—and long-term advantage.
Step 1: Define Your Long-Term Business and Wealth Goals
Any effective Multi-year Tax Strategy must be anchored to clear objectives. Are you building the business to sell in 5–10 years? Are you aiming to own multiple locations or properties? Do you want the company to fund a specific retirement lifestyle or legacy for your family? Clarifying these goals gives your tax planning a direction, not just a destination of “pay less this year.”
Step 2: Map a 3–5 Year Financial and Tax Forecast
Next, work with a strategic advisor to sketch out a realistic 3–5 year projection of revenue, profit, major investments, and potential exits. This does not have to be perfect, but it should be thoughtful. From there, you can begin to overlay:
When to plan major purchases or real estate moves
How to structure depreciation and financing to support that timeline
Which credits and incentives are most likely to apply and when
This forecast becomes the backbone of your Long-term Wealth Planning as a business owner. It gives you a strategic view that can be refined each year as reality unfolds.
Step 3: Coordinate with a Strategically Minded Tax Partner
Not every tax professional is set up for this kind of work. Many are excellent at compliance—getting returns filed correctly and on time—but are not focused on proactive, multi-year design. Partnering with a firm like Big Life Financial, which emphasizes strategic Multi-year Tax Strategy and Long-term Wealth Planning, ensures that your ideas translate into concrete, compliant actions year after year.
Step 4: Review and Adjust Annually
A multi-year plan is not a static document. Markets change, tax laws evolve, and your business will not grow in a perfectly straight line. The key is to review your strategy each year—not just to look back at what happened, but to refine the next several moves. This is how high-level organizations operate, and it is how your business can ensure its tax strategy stays aligned with reality and opportunity.
From Annual Stress to Strategic Advantage
Planning taxes one year at a time keeps you on a treadmill—running hard, but never getting ahead. Multi-year planning, by contrast, turns taxes into a strategic lever. It helps you coordinate real estate, depreciation, credits, and cash flow into a cohesive plan that supports your Long-term Wealth Planning, not just your next filing deadline.
Local businesses that embrace this approach start to think more like high-level organizations and investors. They gain clarity about the future, reduce unpleasant surprises, and consistently keep more of what they earn—year after year. With the right partner, such as Big Life Financial, multi-year tax strategy becomes less about complexity and more about confidence: knowing that your decisions today are building the financial future you actually want.
The question is no longer “How do we pay less tax this year?” It becomes “How do we design the next five to ten years so that taxes support our growth, our wealth, and our biggest goals?” When you start asking that question—and acting on it—you move from reactive taxpayer to strategic wealth builder. That is the real power of Multi-year Tax Strategy for your business and your life.
Learning doesn't stop with one article. Watch the full video to explore the conversation in greater detail and gain even more practical insights from the Big Life Financial team.
