Involve Kids in Investments: Secure Their Future
Financial Education, Local Business, Heirs Financial Literacy
Real‑World Financial Education for Future Heirs
Business owners think in decades, not days. You invest in your community, your employees, and your family’s future. Yet one of the most overlooked investments is preparing your children and heirs to understand how money really works—especially when it comes to assets like rental properties and business holdings. Thoughtful, hands‑on financial education today can protect everything you are building for tomorrow.
Why Local Business Owners Need a Different Kind of Financial Education for Their Kids
As a local business owner, your financial life is more complex than a standard paycheck‑and‑401(k) household. You may own rental properties, commercial real estate, equipment, vehicles, or multiple business entities. These assets can provide long‑term security for your family—but only if your heirs know how to manage them, evaluate performance, and make smart decisions when you are no longer at the helm.
Traditional school curriculum rarely covers topics like cash flow analysis, capitalization rates, or how to compare one investment property to another. That gap leaves many heirs unprepared, even when they inherit substantial assets. Heirs Financial Literacy must go beyond theory to include real numbers, real properties, and real decisions—the same way you learned in your business, often by doing.
This is where rental property analysis becomes a powerful teaching tool. By involving your children in the ongoing review of your properties, you create a living classroom. They do not just hear about Financial Education—they experience it in action, with money that matters and outcomes they can see in your family’s life and business.
Turning Rental Properties into a Classroom: Learning Through Analysis
You do not need to be a Wall Street analyst to teach your kids investment fundamentals. Your existing rental properties—whether residential, commercial, or mixed‑use—are ideal case studies. The numbers are real, the decisions are meaningful, and the stakes are high enough to be interesting, but controlled enough to be safe when guided by you and trusted advisors such as Big Life Financial.
Step 1: Start with the Story Behind Each Property
Before diving into spreadsheets, begin with the story. Kids and teens connect more deeply when they understand why you bought a property:
What problem were you trying to solve—cash flow, diversification, retirement income, or a place for your business to operate?
How did you choose the neighborhood or location? Was it close to your shop or in a growing part of town?
What were you nervous about at the time—vacancies, repairs, financing, or managing tenants while running your business?
Framing each property as a real‑world decision you made helps your children see investments as purposeful tools, not mysterious numbers. It is the first step in building practical Heirs Financial Literacy.
Step 2: Walk Through Income and Expenses Together
Next, introduce the basic income and expense categories for each property. This is where the math becomes real. Sit down once a quarter—just like a business review—and go line by line:
Rental income: monthly rent, parking fees, storage, or other revenue sources.
Fixed expenses: mortgage payment, property taxes, insurance, HOA fees, and utilities you cover as the owner.
Variable expenses: maintenance, repairs, landscaping, property management, and vacancy periods.
Have your children help enter these numbers into a simple spreadsheet. Ask them to calculate monthly and annual cash flow: income minus expenses. Over time, they will see patterns—how a single repair can wipe out a month’s profit, or how a rent increase affects the annual return. This is Financial Education at its most practical and memorable.
Step 3: Introduce Key Rental Metrics in Plain Language
Once your kids are comfortable with income and expenses, you can introduce a few simple performance metrics. You do not have to use jargon; just connect each concept to a question they already understand:
Cash‑on‑cash return: “For every dollar we put in, how many dollars come back to us each year?”
Cap rate (capitalization rate): “If we bought this property in cash, what percentage would we earn from rent after expenses?”
Vacancy rate: “How often is the property empty and not bringing in money?”
By tying each metric to a real property they know—perhaps the duplex down the street or the small commercial building that houses your shop—you help them internalize what “good” and “bad” performance looks like. That understanding will be invaluable when they someday oversee your portfolio or make their own investment choices.
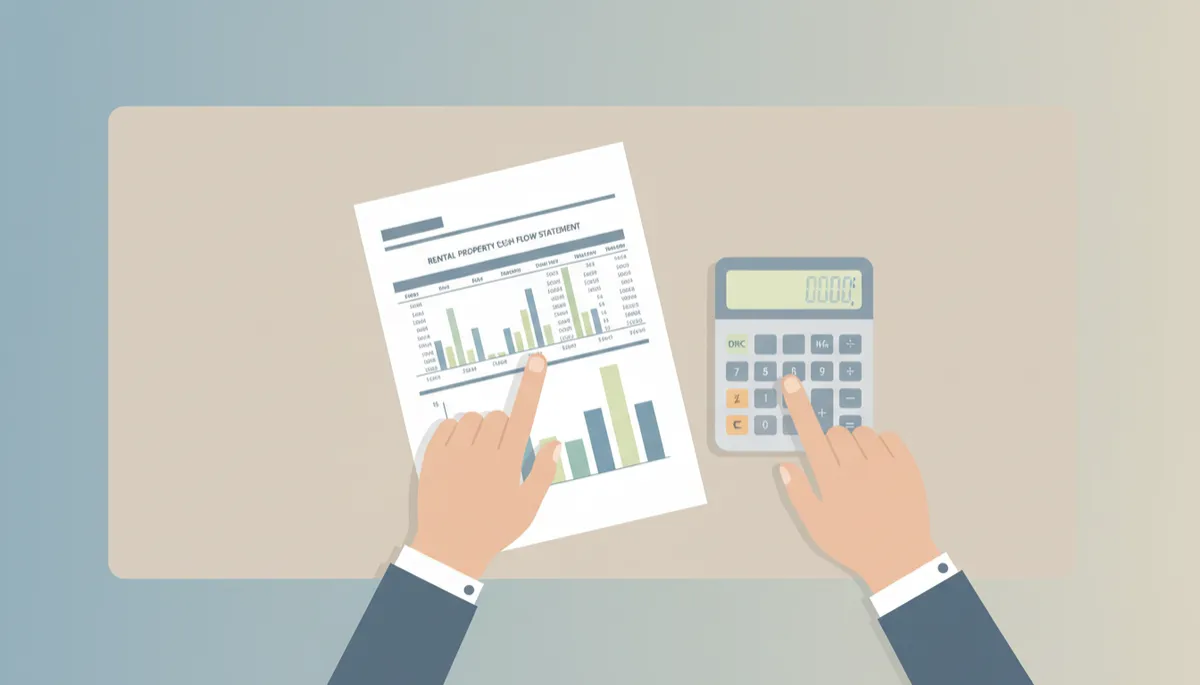
Reviewing real cash flow statements turns abstract financial ideas into practical, memorable lessons.
Understanding Investment Performance: Real‑World Education for Future Heirs
For your children to someday step confidently into ownership—of your rentals, your business, or both—they must learn to do what you do instinctively: evaluate performance and make decisions. That is the heart of Heirs Financial Literacy. Rental properties offer a safe, structured way to build this skill long before inheritance is on the horizon.
Comparing Properties: Which Investment Is Working Hardest?
Once your kids understand the basics for one property, begin comparing two or three. This is where investment analysis becomes engaging—almost like a strategy game. Lay out the numbers side by side and ask questions such as:
Which property produces the most cash flow each month?
Which has the highest cash‑on‑cash return, and why might that be?
Is there a property that creates more headaches than it is worth—constant repairs, difficult tenants, or frequent vacancies?
Invite your children to form an opinion: “If you were in charge, which property would you keep, improve, or consider selling?” They learn that performance is not just about the biggest building or the highest rent—it is about how well each asset supports your family’s goals and your local business strategy.
Connecting Investment Performance to Family and Community Goals
Numbers alone are not enough. To create meaningful Financial Education, tie performance back to what your family cares about. For example:
“This property’s cash flow helps us pay for your college, support our employees during slow seasons, or donate to local charities.”
“If this building underperforms for several years, it could limit our ability to expand the business or buy another property.”
“Improving this property—by renovating units or upgrading signage—could increase its value and strengthen our long‑term financial security.”
When children see how investment decisions ripple through your business, your household, and the local community, they begin to appreciate the responsibility that comes with wealth. That emotional connection is a critical part of Heirs Financial Literacy and one that cannot be taught from a textbook.
Teaching Risk, Reserves, and Long‑Term Thinking
Real‑world investment education must also include the less glamorous side of ownership: risk and reserves. Use your rental properties to explain why you keep cash set aside, carry insurance, and sometimes say “no” to tempting opportunities:
Walk through a year when a major repair occurred—like a new roof or HVAC system—and show how reserves protected the family budget and the business.
Explain how you choose insurance coverage, and what would happen if a tenant stopped paying or a storm damaged the building.
Discuss why you might keep a stable, moderately performing property instead of chasing riskier “hot” deals.
These conversations build judgment. Your children start to see that successful investors—and successful local business owners—win by managing downside risk, not just by pursuing upside potential. That mindset will serve them in every financial decision they make, from their first car loan to leading your company or rental portfolio someday.
Practical Ways Local Businesses Can Involve Kids in Investment Decisions
You are already busy running your business and managing properties. The good news is that building Heirs Financial Literacy does not require a separate curriculum—it can be woven into what you are already doing. Here are practical, time‑efficient ways to involve your children at different ages.
Ages 10–13: Simple Exposure and Vocabulary
At this stage, your goal is to make investments feel normal, not intimidating. Consider:
Driving by your rental properties and briefly explaining what they are and why you own them.
Letting them help collect rent checks (where appropriate) or see electronic transfers hit the account.
Introducing basic terms like “rent,” “mortgage,” “profit,” and “repairs” in everyday language.
Ages 14–17: Hands‑On Analysis and Decision Input
Teens are ready for deeper involvement. You can:
Have them enter income and expense data into spreadsheets for each property and calculate cash flow.
Ask them to prepare a simple one‑page “property report” for a quarterly family meeting, summarizing performance and any issues.
Involve them in discussions about rent increases, cosmetic upgrades, or whether to renew a lease with a challenging tenant.
Ages 18 and Up: Shared Responsibility and Strategic Planning
Young adults can begin to share real responsibility under your guidance and with support from professionals like Big Life Financial:
Invite them to attend meetings with your property manager, banker, or financial strategist so they see how decisions are made.
Give them a specific role, such as overseeing one property’s marketing or tracking maintenance schedules and costs.
Begin including them in high‑level conversations about succession planning, estate strategies, and how rental properties fit into the broader family wealth plan.
The Role of Professional Guidance: How Big Life Financial Supports Local Families
While you bring real‑world experience and deep knowledge of your local market, you do not have to handle Financial Education alone. A strategic partner like Big Life Financial can help you design a clear, age‑appropriate roadmap for teaching your heirs, while also optimizing the performance of your rental properties and business assets.
For many local business owners, the biggest fear is not taxes or market swings—it is that their children will inherit significant assets without the wisdom to manage them. Big Life Financial specializes in helping families turn their existing investments into teaching tools, integrating Heirs Financial Literacy directly into the long‑term wealth strategy. That might include:
Creating simple, customized rental property dashboards your kids can understand and help maintain.
Facilitating family meetings where performance, goals, and responsibilities are discussed in a structured, supportive environment.
Aligning your insurance, entity structure, and estate planning with your education goals so heirs are protected and prepared.
Why This Matters Now: Protecting the Legacy of Local Businesses
Across the country, communities are watching long‑standing local businesses and family‑owned rental portfolios disappear within a generation. Often, the issue is not the market—it is a lack of preparation. Heirs inherit properties or companies they do not understand, feel overwhelmed, and quickly sell to outside buyers who have no connection to the town or its people.
By involving your children in rental property analysis and investment decision‑making today, you dramatically increase the odds that your life’s work will remain in capable hands tomorrow. You are not just leaving assets; you are leaving a skill set, a mindset, and a sense of stewardship. That is the true power of intentional Financial Education for heirs.
Ready to Turn Your Properties into a Living Classroom? Big Life Financial Can Help.
You have already done the hard part—building a business, acquiring properties, and caring about what happens after you are gone. The next step is to make sure your children are ready to carry that legacy forward with confidence. That is where Big Life Financial comes in.
Big Life Financial works with local business owners and real estate investors to design customized Financial Education plans for their families. Together, we help you:
Turn your existing rental properties into clear, engaging teaching tools for your kids and grandkids.
Build a step‑by‑step roadmap for Heirs Financial Literacy, from simple exposure to shared decision‑making.
Align your investment strategy, tax planning, and estate documents so your wealth is protected and your wishes are clear.
📌 Key Takeaway: The most valuable thing you can leave your heirs is not just property—it is the confidence and competence to manage it well. That requires intentional, real‑world Financial Education, starting now.
If you are a local business owner with rental properties, you are sitting on one of the best educational platforms available. Do not wait for a crisis or a transition to start teaching. Partner with Big Life Financial to create a thoughtful, practical plan that fits your schedule, your values, and your unique portfolio.
Ready to turn your investments into a classroom and your heirs into capable stewards of your legacy? Contact Big Life Financial today to schedule a conversation about your rental properties, your business, and your family’s future. Together, we will build a plan that helps your children learn, grow, and someday lead—with clarity, confidence, and purpose.
If you enjoyed this article, you’ll find even more helpful insights in the full Big Life Financial YouTube video. Give it a watch!
