Tax Advice for High-Income Earners
Tax Planning, High-Income Tax, Financial Strategy
Why High-Income Earners Need Different Tax Advice
Once your income crosses into the high six figures, the tax rules start to feel very different. Strategies that worked when you earned $120,000 fall flat at $320,000. At this level, tax planning challenges multiply, generic tax strategies lose their power, and many people quietly realize they may have outgrown CPA services that were perfectly fine a few years ago. This is where a more sophisticated, proactive approach—like the one we use at Big Life Financial—can make an enormous difference to your long-term wealth.
When Your Income Crosses $300,000, the Tax Game Changes
For many professionals, business owners, and successful executives, the $300,000 mark is a turning point. It’s often the moment when taxes stop being an annoying bill and start feeling like your single largest expense. The U.S. tax code is deliberately structured so that as income rises, both the rates and the complexity of high-income tax rules increase. That means your approach must evolve, too.
The Hidden Tax Planning Challenges Above $300,000
Once your income climbs into the $300,000+ range, you’re suddenly exposed to a web of tax planning challenges that most people never have to think about. These include:
Phase-outs of deductions and credits: Popular tax breaks quietly disappear as your income rises, driving up your effective tax rate, not just your marginal rate.
Additional Medicare and Net Investment Income Taxes: High earners may owe extra taxes on wages, self-employment income, and investment income that many CPAs barely mention in casual conversations.
Alternative Minimum Tax (AMT) exposure: Certain deductions and incentive stock options can trigger AMT, catching high-income professionals off guard if no one is modeling the impact in advance.
Complex equity compensation: RSUs, ISOs, NSOs, and performance shares come with their own timing and tax consequences that can dramatically increase your bill if handled reactively instead of strategically.
These tax planning challenges are not theoretical. For a household earning $350,000–$500,000, it’s common to see five-figure differences in annual tax bills based purely on how income and deductions are structured and timed. That’s why different tax advice—more proactive, more strategic, and more tailored—is essential at this level.
Why Generic Tax Strategies Stop Working for High Earners
Most of us are taught a handful of basic, almost cliché generic tax strategies: contribute to your 401(k), claim your mortgage interest, save receipts for deductions, and maybe toss something into an IRA. These are fine starting points, but for high-income tax situations, they’re rarely enough to move the needle.
The Limits of “Check-the-Box” Tax Advice
Generic tax strategies are designed for the average taxpayer. They assume W-2 income, a simple investment account, maybe a home, and not much else. But if you’re a physician with multiple practice locations, a tech executive with concentrated stock, or a business owner with several entities, your situation is far from average.
Standard deductions vs. strategic deductions: At high incomes, you need to think about what you deduct, when you deduct it, and which entity takes the deduction—not just whether you have receipts in a folder.
Simple retirement contributions vs. multi-layer planning: High earners may benefit from cash balance plans, defined benefit plans, backdoor Roth strategies, or entity-level retirement plans that go far beyond a standard 401(k).
Basic itemizing vs. advanced coordination: Charitable giving, medical expenses, and property taxes can be coordinated across years and entities to smooth out spikes in taxable income and avoid hidden thresholds.
💡 Friendly Insight from Big Life Financial: If your tax strategy still fits on a single page, but your income has grown beyond $300,000, there’s a strong chance you’re leaving money on the table every year.
The Cost of Relying on Generic Tax Strategies
The problem with generic advice isn’t that it’s wrong; it’s that it’s incomplete. For a high-income household, “good enough” can quietly cost tens or even hundreds of thousands of dollars over a decade. Consider a few common scenarios:
A business owner who never restructures their entity might miss out on opportunities to split income, leverage the Qualified Business Income deduction, or shift income to family members in lower brackets, all of which are powerful tools in high-income tax planning.
A professional with large RSU vesting events who doesn’t plan the timing or coordinate with charitable strategies may pay unnecessary taxes on windfall years instead of smoothing income over time.
A couple with significant investment income who never looks at asset location (which investments go in which accounts) may pay far more in annual tax drag than necessary.
In each of these cases, generic tax strategies—“max the 401(k), keep receipts, use a CPA to file”—simply don’t go far enough. They don’t address the unique tax planning challenges that emerge when your income and assets reach a different league.
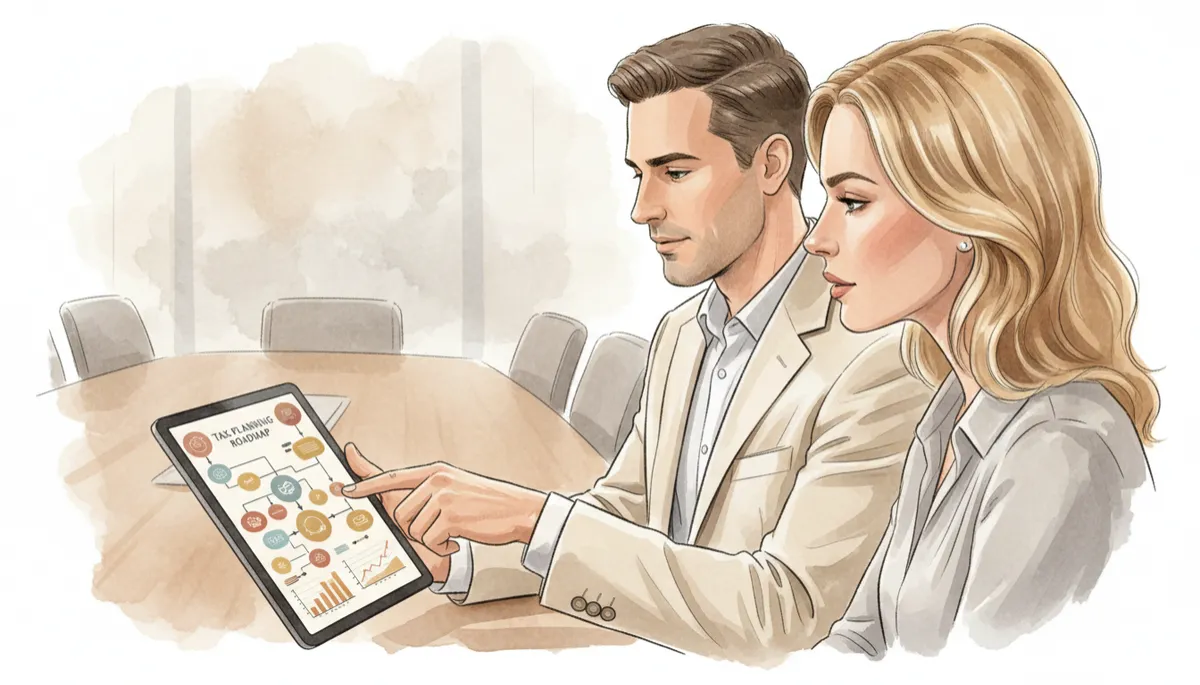
A tailored roadmap often reveals five-figure annual savings for high-income households.
Signs You’ve Outgrown Your CPA (and What to Do About It)
Many high earners have a loyal relationship with a long-time tax preparer. That person might be excellent at filing returns accurately and on time. But there’s a difference between compliance work and strategic advice. One of the most important financial milestones for high-income professionals is recognizing when you’ve quietly outgrown CPA services that are focused only on last year’s forms.
Red Flags That Your Tax Advice Is Stuck in “Basic Mode”
Here are some clear indicators that your needs have moved beyond what your current CPA is delivering:
Your tax conversations happen once a year. If you only speak to your CPA during tax season, you’re getting compliance, not planning. True high-income tax strategy happens year-round.
You’re always looking backward. If the main discussion is “Here’s what you owe for last year,” and not “Here’s how we can reduce what you owe next year,” you’ve likely outgrown CPA services focused only on history.
Your CPA doesn’t ask about your goals. Advanced tax planning connects to your bigger picture: retirement, business exits, college funding, real estate, and legacy. If no one is asking where you want to be in 5–10 years, your strategy will stay shallow.
Complex issues get brushed aside. If questions about stock options, multi-state income, or new entities are met with “We’ll just see how it shakes out at tax time,” that’s a sign your advisor may be out of their depth for your level of complexity.
📌 Key Takeaway: Identifying when you’ve outgrown your CPA isn’t about blame—it’s about recognizing that your financial life has evolved and your advisory team needs to evolve with it.
What a High-Income Tax Planning Team Should Provide
When your income rises, you don’t just need a more experienced CPA—you need a more integrated approach. At Big Life Financial, we think of tax strategy as one part of a coordinated wealth plan. A strong team for high earners should offer:
Proactive planning meetings: At least once or twice a year, you should review projections, explore scenarios, and decide on specific moves before December 31, not after.
Entity and compensation strategy: Guidance on how to structure businesses, compensation packages, and benefit plans to reduce taxes while aligning with your long-term goals.
Investment and tax coordination: Collaboration between your tax professional and financial advisor so that investment decisions consider both growth and tax efficiency.
Scenario modeling: Tools and expertise to model “what if” situations—selling a business, exercising options, buying property—so you understand the tax impact before you act.
Moving Beyond Generic Tax Strategies: What High Earners Can Do Now
If you’re earning more than $300,000 and suspect that your tax plan hasn’t kept pace with your income, you’re not alone. The good news is that you don’t need to become a tax expert yourself. You simply need to ask better questions and surround yourself with advisors who specialize in high-income tax planning.
Step 1: Get Clear on Your True Tax Picture
Start by understanding where you are today. Ask your current CPA or advisor for:
A summary of your effective tax rate over the last 2–3 years, not just the marginal rate.
A breakdown of where your income is coming from (wages, business, investments, real estate, equity compensation, etc.).
A list of the top strategies they are using today to reduce your taxes— and how much each one is actually saving you.
If this information is hard to obtain, vague, or nonexistent, that’s a strong signal that you may have outgrown CPA services that are focused only on form-filing rather than strategy.
Step 2: Ask Strategic, Forward-Looking Questions
Next, start shifting the conversation from “What happened last year?” to “What should we do this year?” Some powerful questions to ask include:
“What are the top three tax planning challenges for someone with my income and situation?”
“Which generic tax strategies I’m using now have essentially maxed out, and what advanced strategies should we consider instead?”
“How can we better coordinate my business, investments, and retirement planning to reduce my overall tax burden over the next 5–10 years?”
The quality of the answers—and how comfortable your advisor is with these questions—will tell you a lot about whether you’re in the right place or if it’s time to upgrade your team.
Step 3: Build a Team That Matches the Size of Your Life
High-income earners don’t just need more advice; they need the right advice, coordinated across professionals. At Big Life Financial, we encourage clients to think of their advisors as a team: financial planner, tax strategist, attorney, and sometimes a business consultant, all working from the same playbook. The goal is not just to lower this year’s tax bill, but to design a structure that supports the “big life” you’re building—more freedom, more options, and more control over where your money goes.
The Bottom Line: Different Income Requires Different Tax Advice
As your income grows, your financial life naturally becomes more complex. What doesn’t change is the basic choice in front of you: accept whatever the system takes, or become intentional about how you navigate it. For high-income earners, the gap between generic and advanced tax planning isn’t just academic—it’s measured in real dollars, real opportunities, and real peace of mind.
If you’re earning above $300,000 and still relying on generic tax strategies, it’s worth asking whether you’ve quietly outgrown your CPA. The tax planning challenges you face now are different from those you had when you were just getting started—and they deserve a different level of attention. With the right team and a proactive plan, you can keep more of what you earn, reduce financial stress, and channel those savings into the life and legacy you actually want.
💬 A Friendly Note from Big Life Financial: You’ve worked hard to create high income. You deserve tax advice that works just as hard for you. Whether you partner with us or another specialist, make sure your advisors are equipped for the level of success you’ve reached—and the level you’re aiming for next.
There’s more to take away than what can fit into one article. Press play and hear the conversation unfold for additional insights, real-world perspectives, and ideas that can give you even more to think about.
