Credentials Aren't Enough: Evaluating Financial Advice
Financial Advice, Expertise Evaluation, Beyond Certifications
Why Credentials Alone Don't Guarantee Good Advice
Professional designations look impressive on a business card, but when it comes to your money and your future, letters after a name are only the starting point. To protect yourself and your goals, you need a results-oriented way to judge real expertise, not just a wall full of certificates.
The Comfort—and Danger—of Impressive Titles
When you meet a new advisor, it is natural to feel reassured by a polished office, framed certificates, and a long list of professional designations. Those signals tell your brain, “This person must know what they’re doing.” In a complex area like money, taxes, or investing, that sense of comfort is powerful. But comfort is not the same as quality. The core idea behind Expertise Evaluation is simple: credentials are clues, not proof. They show that someone has completed a course, passed an exam, or joined a professional body. They do not automatically prove that this person gives good, unbiased, or effective advice in the real world.
At Big Life Financial, we meet many clients who assumed their previous advisor was excellent simply because of a title. Later, they discover high fees, unnecessary products, or missed opportunities that cost them years of progress. The lesson is not to distrust every designation, but to understand its limits and look beyond certifications before you place your financial life in someone’s hands.
1. Understanding the Limits of Professional Designations
Professional designations can absolutely be valuable. Many require rigorous study, ongoing education, and adherence to ethical standards. The issue is not that designations are meaningless—it is that they are incomplete. They tell you about a person’s minimum technical knowledge, not about how they think, behave, or perform when it matters most for you.
Designations measure exams, not outcomes. Passing a test proves someone understood content at a point in time. It does not show whether their clients are reaching their goals, managing risk wisely, or avoiding unnecessary debt and taxes.
Ethics codes are only as strong as enforcement. Many professional bodies have codes of conduct, but enforcement can be slow or limited. A person can hold a respected title and still give advice that is legal yet misaligned with your best interests.
Some designations are marketing tools. Not all letters carry the same weight. A weekend course can lead to a shiny new acronym that sounds impressive but adds little real skill. This is one reason a thoughtful Expertise Evaluation process matters so much.
Even the most respected professional designations cannot account for personal qualities that deeply affect the quality of advice: listening skills, curiosity, humility, and willingness to say, “I don’t know, but I’ll find out.” These traits rarely show up on a certificate, yet they often separate average advisors from truly great ones.
💡 Pro Tip: When you see a designation, ask what it actually required—hours of study, exams, casework, or just a short seminar and a fee.
2. Looking Beyond Titles and Certifications
To move beyond certifications, you need to shift your mindset from “Who sounds impressive?” to “Who is the right partner for my specific situation?” That shift changes the questions you ask and the way you interpret the answers. Instead of being dazzled by a long title, you become curious about how this person actually works, thinks, and measures success with clients like you.
Ask About Process, Not Just Background
Background matters, but process tells you how advice is created. Two advisors with identical professional designations can follow very different paths with clients. When you are doing your own Expertise Evaluation, consider questions like:
“How do you get to know a new client’s goals and concerns?”
“What steps do you follow before making a recommendation?”
“How often do you review and adjust a plan when life changes?”
A thoughtful, structured process is a strong sign of real expertise. A vague or salesy answer—especially one that jumps quickly to products—can be a warning sign, no matter how many certificates are on the wall.
Clarify Incentives and Conflicts of Interest
A key part of going beyond titles is understanding how an advisor gets paid. Even highly credentialed professionals can be influenced by commissions, sales targets, or company quotas. None of these are necessarily evil, but they can quietly shape the advice you receive. A truly results-oriented advisor should be transparent about:
Whether they earn commissions, fees, or a combination of both
Any incentives they receive for recommending particular products or strategies
Whether they are required to sell or prioritize certain company offerings
At Big Life Financial, for example, we emphasize clarity around compensation because it helps clients trust that our recommendations are built around their goals, not our quotas. This kind of transparency is just as important as any designation when you are evaluating expertise.
Look for Communication Skills and Empathy
Great advice is useless if you do not understand it or feel comfortable asking questions. Communication and empathy are critical parts of Expertise Evaluation that rarely appear in a list of professional designations. Notice whether the advisor:
Explains concepts in plain language, without making you feel small or uninformed
Listens more than they talk in the first meeting
Shows genuine interest in your story, not just your account balances
These “soft skills” are actually hard requirements if you want advice that fits your life. They are a major part of why some advisors with modest resumes deliver better outcomes than others with long lists of titles.
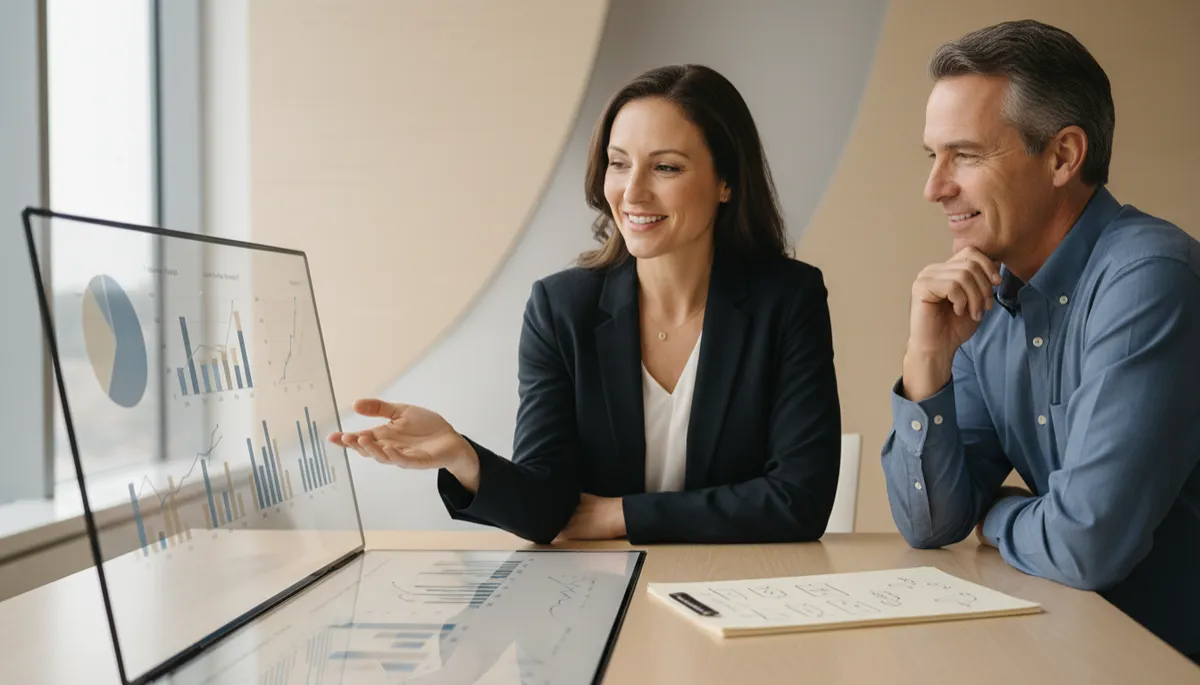
Clear communication turns complex strategies into confident, results-oriented decisions.
3. Evaluating Expertise Through Results, Not Just Résumés
The most powerful way to move beyond certifications is to ask, “What happens for clients who work with you?” A truly results-oriented advisor can describe patterns of outcomes, not just credentials. They may not share individual stories in detail, but they can talk about the kinds of progress clients usually see over time and how they measure success together.
What “Results” Really Mean in Financial Advice
In investing, people often think “results” means beating the market every year. In real life, results are more personal and more practical. A smart Expertise Evaluation looks for evidence that an advisor helps clients:
Define clear, realistic goals (like buying a home, paying for college, or retiring earlier)
Stay on track through market ups and downs without panic decisions
Reduce unnecessary taxes, fees, and debts that quietly drain wealth
Build habits—saving, reviewing, adjusting—that compound over years
These are the kinds of outcomes that change lives, and they rarely depend on a single clever product or secret strategy. They depend on consistent, thoughtful guidance tailored to your situation. That is why Big Life Financial focuses on long-term progress and decision quality, not just short-term performance snapshots.
Questions That Reveal Real-World Performance
You do not need to be an expert yourself to evaluate whether an advisor is truly results-oriented. You just need the right questions. Here are a few that can open deeper conversations:
“How do you measure success with your clients?” Look for answers that mention progress toward goals, behavior during tough times, and overall financial health—not just investment returns.
“Can you share examples of how you’ve helped clients through major life changes?” For instance, job loss, business transitions, or caring for aging parents. You are listening for thoughtful, human stories, not generic sales pitches.
“What do you do when a client’s plan isn’t working as expected?” Real experts adjust, communicate, and learn. Overconfident advisors may insist their original idea is perfect despite new information.
📌 Key Takeaway: A strong track record is about how clients live and feel, not just what their statements say in one particular year.
The Role of Fit in Expertise Evaluation
One more subtle but important point: “good advice” is not one-size-fits-all. An advisor can be highly skilled and still be the wrong fit for you. For example, someone who specializes in high-net-worth retirees may not be ideal if you are an entrepreneur in your 30s juggling growth and cash flow. A careful Expertise Evaluation includes fit:
Do they regularly work with people in your stage of life or business?
Do they understand the specific challenges you face—like variable income, stock options, or caring for kids and parents at the same time?
Does their style match yours—more collaborative, more directive, more educational?
At Big Life Financial, we often say, “The right advisor is someone you can see yourself calling on your best days and your worst days.” That kind of relationship cannot be captured in a designation, but it dramatically affects the quality and impact of the advice you receive.
Building Your Own Framework for Evaluating Advisors
To bring all of this together, it helps to have a simple framework you can use whenever you are choosing or reviewing a financial consultant. Think of it as your personal checklist for Expertise Evaluation—one that keeps you focused on what truly matters: outcomes, alignment, and trust.
A Simple Three-Part Checklist
Credentials and Knowledge: Do they have relevant professional designations and ongoing education? This is your baseline—necessary but not sufficient.
Process and Fit: Do they have a clear, thoughtful process? Do they understand your situation and communicate in a way that works for you? This is where you move beyond certifications into real partnership.
Results and Accountability: Can they describe how clients typically progress? Do they review and adjust plans regularly? Are they willing to be measured against your goals? This is where a truly results-oriented advisor stands out.
You do not need to interrogate anyone or turn the meeting into an exam. Instead, think of it as a conversation where you are gathering clues. Over time, the pattern becomes clear: some advisors lean heavily on titles, while others demonstrate depth, humility, and a track record of helping clients build the lives they want.
Bringing It Back to Your Big Life
Your money touches almost every part of your life—where you live, how you work, the opportunities you can offer your family, and the freedom you feel day to day. That is why choosing an advisor is such a meaningful decision. Credentials can open the door, but they should never close the conversation. By understanding the limits of professional designations, looking beyond titles and certifications, and focusing on a results-oriented relationship, you give yourself a much better chance of receiving advice that truly serves you.
At Big Life Financial, our goal is right there in our name: to help you build a big life, not just a big account balance. That means listening carefully, designing strategies around your values, and walking with you as your circumstances evolve. We are proud of the expertise our team brings—but we know that, in the end, what matters most is how that expertise shows up in your results, your confidence, and your sense of possibility.
💬 Next Step: If you are rethinking a current advisory relationship or choosing one for the first time, use the ideas in this article as your guide. Ask deeper questions, look for real-world outcomes, and remember: the best advisor for you is the one who proves their value through consistent, meaningful results—not just the letters after their name.
We’ve covered the key ideas, but there’s always another layer worth exploring. If you want to hear more of the thinking behind them, take a few minutes to watch the video and let the conversation give you a different perspective.
