
Claim Missed R&D Credits by 2026 Deadline
Taxes, R&D Credits, Small Business Savings
The 2026 Deadline You Can’t Ignore: How to Claim Missed R&D Credits from Past Years
A one‑time tax window is opening that could put tens of thousands of dollars back in your pocket. If you did any kind of product, software, or process development between 2022 and 2024, you may have unclaimed R&D tax credits sitting on the table — but only until 2026.
Why 2026 Is Such a Big Deal for Missed R&D Credits
For years, the federal Research & Development (R&D) tax credit has been one of the most powerful, legal ways for innovative businesses to cut their tax bill. Yet thousands of founders, consultants, software developers, engineers, and small business owners never claimed what they were entitled to — often because the rules seemed confusing, or their CPAs were focused only on basic compliance.
Thanks to recent law changes, 2026 creates a rare combination of opportunities: a three‑year lookback period for missed credits, retroactive relief for 2022–2024 expenses, and clear deadlines that force the IRS — and taxpayers — to act. If you ignore this window, the money simply expires. If you use it strategically, it can translate into meaningful cash refunds or future tax savings.
📌 Key Takeaway: You may be able to reach back to 2022, clean up the confusing 2022–2024 period, and pull real cash out of work you’ve already done — but only if you move before the 2026 deadlines hit.
1. What Changed Between 2022–2024 — And Why So Many People Missed Out
To understand why 2026 matters, you first need to understand the mess that started in 2022. Before that year, U.S. businesses could generally immediately deduct their domestic R&D costs. Then a change in the tax law kicked in, forcing companies to capitalize and amortize those costs over five years for U.S. research and 15 years for foreign research (under Section 174). That meant higher taxable income in the short term, more complexity, and a lot of confusion around how deductions and credits interacted.
At the same time, the R&D tax credit (under Section 41) technically remained available. But in practice, many small and mid‑sized businesses simply backed away. Here’s why credits were badly underused from 2022–2024:
Confusing timing rules: Deductions were pushed out over years, while credits were still calculated annually. Many owners and even CPAs weren’t sure how to coordinate the two, so they just skipped the credit entirely.
Fear of IRS scrutiny: The IRS made clear that R&D credits were an enforcement priority, increasing audits and pushing for stronger documentation. Without clear systems in place, businesses felt the risk outweighed the reward.
Section 174 confusion: Many companies didn’t even realize that their software development, process improvements, or product experiments fell under Section 174 rules — or that they could still generate R&D credits on top of those costs.
CPAs overwhelmed with change: Between pandemic relief programs, new forms, and changing guidance, many generalist tax preparers did not have the bandwidth to dig into specialized R&D planning for smaller clients.
The result? Billions of dollars in legitimate R&D credits went unclaimed nationwide between 2022 and 2024 — especially by exactly the kinds of innovative small businesses Congress intended to help.
2. The 2025 Rule Update: Why It Matters Right Now
In response to the backlash from business owners, Congress passed the One Big Beautiful Bill Act (OBBBA), which dramatically improved the landscape starting in 2025 and 2026. The single biggest win for innovators: immediate expensing of domestic R&D under Section 174A for tax years beginning after December 31, 2024.
In plain English, that means if you’re doing research, experimentation, software development, or process improvements in the U.S. in 2025 and beyond, you can once again deduct those costs in the year you incur them, instead of stretching them out over five years. This change lines up the timing of your deductions with your R&D credit calculations, making the credit more valuable and easier to plan around.
But the 2025 update did something even more powerful for small businesses: it created a retroactive election for 2022–2024. If your average gross receipts are under roughly $31 million, you may be able to apply Section 174A to those earlier years — either by amending your returns or by spreading the deductions into 2025–2026. That’s where the 2026 deadline becomes critical, because you only have a limited window to make that election and lock in the benefits.
💡 Pro Tip: The 2025 rule update isn’t just about future savings. It’s your chance to fix 2022–2024 and recover cash you should have had all along.
3. How Far Back You Can Go: Understanding the 3‑Year Lookback
The IRS generally allows you to amend income tax returns for up to three years after the original filing date. That “statute of limitations” is what creates a rolling three‑year lookback for R&D credits. In practice, this means you can often:
Amend the last three filed returns to add missed R&D credits, and
Potentially pair those credits with the new Section 174A expensing rules if you qualify for the retroactive election.
For many small businesses, that means 2023, 2024, and 2025 are in play right now — and 2022 may still be reachable depending on when you filed and how you use the retroactive election. On top of that, there is a specific federal deadline: eligible small businesses must file any retroactive Section 174A elections or amendments by July 6, 2026.
Miss that date, and the door slams shut. Your ability to treat 2022–2024 expenses more favorably — and to align them with missed R&D credits — can disappear overnight. There’s also a 45‑day “perfection transition period” for R&D refund claims that ends January 10, 2027, which affects how much time you have to fix incomplete claims after filing.
⚠️ Warning: Every month you wait, another year can drop off the back of your three‑year window. If you had heavy development spending in 2022 or 2023, delaying could literally erase that year’s refund opportunity forever.
4. How Much Money Is Really on the Line? Realistic Refund Ranges
The R&D credit is a dollar‑for‑dollar reduction of your tax liability. In other words, it’s not just a deduction that lowers taxable income — it directly cuts the tax bill itself. When you stack multiple years together, the numbers can become surprisingly large, even for modest‑sized businesses or solo founders with a small team.
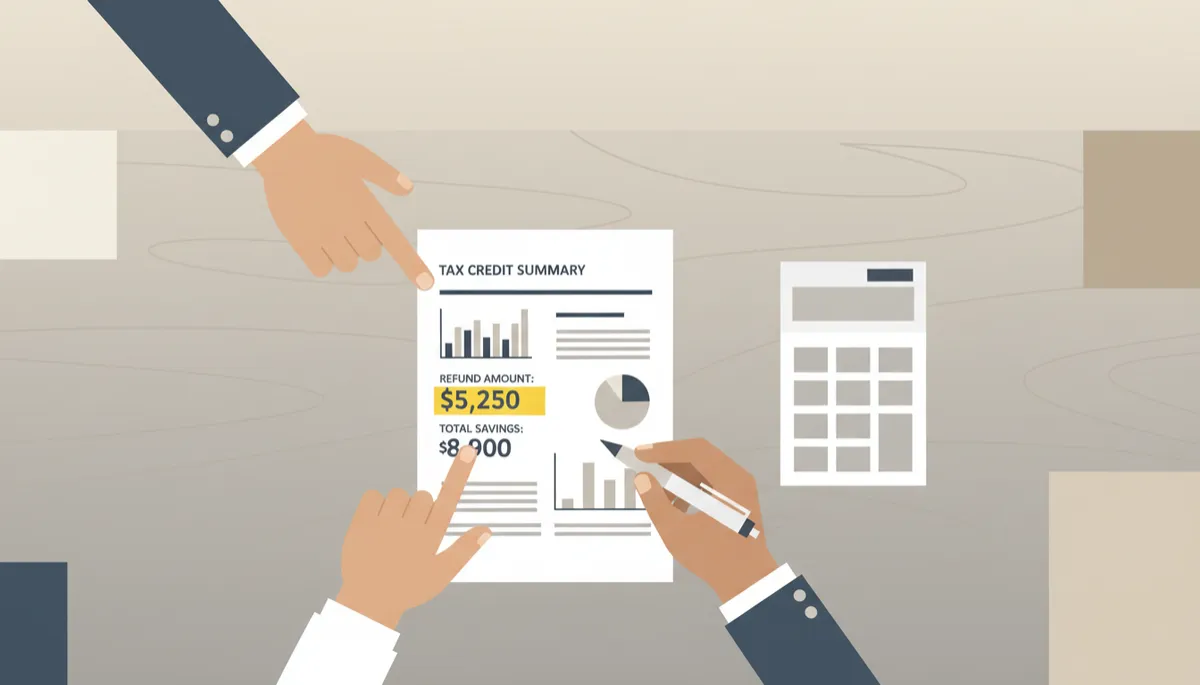
-toned close-up of hands pointing at a printed tax credit summary showing refund amounts and...
Stacking three years of missed credits can turn routine R&D work into meaningful cash refunds.
While exact amounts always depend on your facts, here are typical ranges we see when helping clients uncover missed credits from past years:
Solo or very small teams (1–5 people): Often $10,000–$40,000 per year in combined federal and state benefits, especially for software, engineering, or technical consulting work.
Growing small businesses (5–25 employees): Commonly $30,000–$150,000 per year, depending on how many people are involved in qualifying projects and their compensation levels.
Established innovators (25–100+ employees): It’s not unusual to see $100,000–$500,000+ per year in credits and deductions when R&D is a core part of the business model.
Now multiply those ranges across three years. A modest $25,000 per year opportunity becomes $75,000. A more substantial $80,000 per year opportunity becomes $240,000. For many business owners, that’s the difference between delaying a key hire or making it, between bootstrapping slowly or funding the next phase of growth from tax savings you already earned.
📌 Key Takeaway: If you spent serious time or money on building, improving, or experimenting with products, software, or processes since 2022, it’s reasonable to think in five‑figure or even six‑figure refund potential — not a few hundred dollars.
5. Step‑by‑Step: How to Claim Missed R&D Credits Before the 2026 Deadline
The good news: you don’t have to guess your way through this. Here is a clear, practical roadmap for taking advantage of the 2026 window and claiming credits you left on the table in 2022–2024.
Step 1: Confirm You’re Doing Qualifying R&D Work
The IRS uses a four‑part test to decide whether your activities qualify for the R&D credit. In simple terms, your work usually qualifies if:
You’re trying to develop or improve a product, process, software, formula, or technique,
The work is based on hard sciences or engineering (for example, computer science, physics, engineering, biology),
There is technical uncertainty at the start — you didn’t already know exactly how to achieve the result, and
You go through a process of experimentation — testing, prototyping, iterating, modeling, or simulating.
This applies far beyond “white lab coat” research. Common qualifying examples include custom software builds, new app features, manufacturing process improvements, automation projects, hardware design, and even internal tools that solve technical problems in your business.
Step 2: Identify Which Years You Can Still Amend
Next, look at your last several tax returns and note:
Which years you filed (2022, 2023, 2024), and
Whether you claimed any R&D credits on Form 6765 for those years.
If you did not claim credits, or you suspect they were significantly under‑calculated, those years are candidates for amendment. Because of the three‑year statute of limitations and the specific July 6, 2026 deadline for retroactive Section 174A elections, timing matters. A specialist can quickly map out exactly which years are still “alive” for you and how the deadlines apply.
Step 3: Gather the Right Documentation (Without Drowning in Paperwork)
Historically, one of the biggest pain points has been documentation. The IRS expects you to tie your R&D claims to specific “business components” — individual products, processes, or software modules — and to show that each one meets the four‑part test. That’s why the IRS is rolling out an updated Form 6765 with new sections and a business‑component‑level Section G, which becomes mandatory for most filers starting in 2026.
For your 2022–2024 lookback, you don’t need perfect time sheets or research diaries, but you do need reasonable support. Typical evidence includes:
Project lists and descriptions (what you were building or improving),
Payroll records for technical staff and founders,
Contractor invoices, material costs, and prototyping expenses, and
Emails, tickets, Git logs, design docs, sprint boards, or test reports that show experimentation and iteration.
💡 Pro Tip: You don’t have to be perfectly organized to qualify. A good R&D specialist will help you reconstruct the story from the systems you already use — like Jira, GitHub, payroll, and project tools.
Step 4: Calculate Your Qualifying Expenses and Credits
Once your projects and supporting records are identified, the next step is to calculate your Qualified Research Expenses (QREs) for each year. These typically include:
Wages for employees directly involved in qualifying R&D activities (and certain supervising or supporting roles),
A portion of contractor costs for qualifying work, and
Supplies and materials consumed in the R&D process (excluding depreciable equipment).
Using those QREs, you or your advisor complete Form 6765, “Credit for Increasing Research Activities”, choosing between the regular calculation method or the Alternative Simplified Credit (ASC) method (IRS Research Credit guidance). The choice can materially affect your credit amount, which is why having an R&D‑focused team model both options is so valuable.
Step 5: File Amended Returns and Retroactive Elections Before the Clock Runs Out
With your credits calculated, your tax professional prepares amended federal (and applicable state) returns for each year you’re reclaiming, attaching Form 6765 and any required statements. If you qualify as a small business under the OBBBA rules, this is also where you make your retroactive Section 174A election for 2022–2024 — potentially improving both your deductions and your credits.
Remember the key dates:
July 6, 2026: Deadline for eligible small businesses to file retroactive Section 174A elections or amended returns for 2022–2024 expenses.
January 10, 2027: End of the 45‑day perfection transition period for R&D refund claims, after which the IRS will be stricter about rejecting incomplete claims outright.
Step 6: Prepare for Stronger Documentation Rules Going Forward
While your immediate focus is capturing past‑year refunds, you also want to position yourself for smooth, low‑stress R&D claims in 2025 and beyond. That means:
Tracking R&D at the business‑component level now, so you’re ready when Section G becomes mandatory for most filers in 2026,
Implementing simple time‑tracking or project‑tagging for technical staff, and
Keeping contemporaneous notes or tickets that show the uncertainty, testing, and iteration in your projects.
Doing this now doesn’t just protect you in case of an audit — it also makes future R&D credit claims faster, easier, and more lucrative.
6. Why This Approach Works: Urgency + Money = Action
At its core, this entire strategy is about two simple realities: time and cash.
The time reality: The 2026 deadlines and the rolling three‑year statute of limitations mean every month that passes can erase a year’s worth of opportunity. Once a year falls off the back of the window, those credits are gone — no matter how innovative or deserving your work was.
The cash reality: We’re not talking about small change. For many founders and business owners, capturing three years of missed credits can mean $50,000–$300,000+ in combined refunds and tax savings. That’s money you can put into hiring, marketing, product development, or simply strengthening your cash reserves.
📌 Key Takeaway: When you combine a hard deadline with a meaningful financial upside, you get a narrow but powerful window to make a high‑impact decision. That’s exactly what the 2026 R&D credit environment creates.
Why Work with Big Life Financial to Capture These Credits
Navigating R&D credits, Section 174A, new Form 6765 rules, and changing IRS expectations is not something most generalist CPAs are set up to do — especially while they’re juggling dozens or hundreds of other clients during tax season. That’s where Big Life Financial comes in.
Big Life Financial specializes in helping innovators, founders, and small‑to‑mid‑sized businesses turn complex tax rules into real cash outcomes. Our approach is designed for exactly this kind of limited‑time opportunity:
We start with a no‑obligation R&D credit assessment to estimate your potential refunds across 2022–2024, so you can see the upside before you commit.
Our team handles the heavy lifting on documentation and calculations, using your existing project tools and payroll data to build a defensible claim that aligns with current IRS guidance.
We coordinate with your existing CPA or tax preparer — or provide a referral — to make sure your amended returns and 174A elections are filed correctly and on time.
We help you build a forward‑looking R&D strategy so you’re not just cleaning up the past, but also maximizing credits and deductions in 2025, 2026, and beyond.
💡 Pro Tip: Even if your CPA told you in the past that you “don’t qualify,” it’s worth a second look. Many professionals underestimate what counts as R&D, especially for software, digital products, and process improvements.
Your Next Move: Don’t Let the 2026 Deadline Pass You By
If you’ve read this far, there’s a good chance you’ve been doing exactly the kind of work the R&D credit was designed to reward — and that you left money on the table between 2022 and 2024. The question is not whether the opportunity exists. It’s whether you’ll capture it before the window closes.
Here’s a simple three‑step action plan you can follow today:
Make a quick list of major development projects, software builds, or process improvements you’ve worked on since 2022.
Pull your last three tax returns and check whether Form 6765 was filed — and if so, whether it truly reflects the scope of your R&D work.
Schedule a call with Big Life Financial to get a tailored estimate of your potential refunds and a concrete plan to file before the 2026 deadlines.
You’ve already done the hard part — taking risks, building new things, solving technical problems. The R&D credit is simply the government’s way of recognizing that effort. The 2026 deadline just means you have to claim your reward on time.
Don’t let another year slip off the three‑year lookback. Don’t wait until July 2026 and find yourself scrambling. Take one focused step now, and turn past innovation into present‑day cash — with a specialist team like Big Life Financial guiding you every step of the way.
Interested in learning more? The full video expands on these ideas with additional context and practical takeaways.
