
Optimize Business Ownership for Tax & Asset Protection
Business Strategy, Tax Planning, Asset Protection
How to Design Business Ownership Structures for Tax Efficiency and Asset Protection
Smart entrepreneurs know that how you own your business can be just as important as the business you build. Thoughtfully designed ownership structures can reduce taxes, shield your assets from lawsuits, and create a smoother path for growth, exit, and generational wealth. This guide walks you through the key strategies—especially the use of trusts, separation of ownership and control, and multi-entity planning—and explains how a coordinated advisory team, like the specialists at Big Life Financial, can help you put it all together.
Why Ownership Structure Matters More Than Ever
Many entrepreneurs pour their energy into sales, operations, and hiring—then default to whatever business structure their first accountant suggested. Years later, they discover they are overpaying in taxes, exposed to unnecessary risk, or facing a messy succession situation. The good news is that with strategic planning, you can:
Reduce current and future tax burdens legally and ethically
Protect your personal wealth from lawsuits, creditors, and business failures
Create a clear roadmap for sale, succession, or generational transfer of the business
Coordinate tax, legal, and financial strategies so they work together instead of at cross-purposes
This is where a specialized firm like Big Life Financial comes in. Their approach goes beyond basic entity selection and digs into how your companies, trusts, and personal finances can be aligned to support a “big life” vision—more wealth, more freedom, and more protection.
Using Trusts to Hold Business Interests
One of the most powerful tools for both tax efficiency and asset protection is the use of trusts to hold your ownership interests in a business. Instead of owning shares or membership interests in your personal name, you can transfer them into a properly designed trust. Done correctly, this can:
Separate your personal assets from business risks and creditors
Create a smoother transition of ownership to heirs or key partners without probate
Offer potential income and estate tax advantages, depending on trust design and jurisdiction
Revocable vs. Irrevocable Trusts for Business Owners
At a high level, business owners typically consider two broad trust categories:
Revocable living trusts – Primarily used for estate planning and probate avoidance. You retain control and can change or revoke the trust. These usually do not provide strong asset protection, but they can still be useful vehicles to hold business interests for smoother transfer at death or disability.
Irrevocable trusts – Often used for asset protection and advanced tax planning. Once assets are transferred, your ability to change the trust is limited, but that very separation can create stronger protection from creditors and potential estate tax benefits for larger estates.
Within these categories, there are many variations—such as grantor trusts, dynasty trusts, and asset protection trusts—each with its own tax and legal implications. The right structure depends on your goals, risk profile, and family situation. This is why Big Life Financial emphasizes customized planning rather than one-size-fits-all templates.
How Trust-Owned Business Interests Work in Practice
Imagine you own 100% of an operating company—say, an LLC that runs your main business. Instead of holding the membership units personally, you can transfer them into a trust. The trust then becomes the legal owner, while you (or another trustee) manage the trust according to its terms. Beneficiaries—such as your spouse, children, or even charities—can receive distributions of income or eventual sale proceeds under rules you define.
This structure can help:
Keep your estate organized and reduce conflict among heirs by clearly spelling out who gets what and when
Prevent a forced sale or fire-sale of the business if something happens to you unexpectedly
Potentially move future appreciation of the business outside of your taxable estate (with certain irrevocable structures)
💡 Pro Tip: Transferring business interests into a trust is not just a paperwork exercise. The valuation, timing, and trust design all affect tax outcomes. Big Life Financial works alongside experienced estate attorneys and valuation professionals to help you avoid costly mistakes.
Separating Ownership and Control for Strategic Tax Planning
A key concept in modern wealth planning is the deliberate separation of ownership and control. You do not always need to personally own an asset to control how it is managed or to benefit from it. This separation can open powerful opportunities for tax planning and asset protection when done within legal guidelines.
Ownership Through Trusts, Control Through Management Roles
When a trust owns your business interests, the trust is the legal owner. However, day-to-day decisions are typically made by:
The trustee, who manages the trust according to its terms, and/or
The managers, directors, or officers of the business entity (such as LLC managers or corporate officers)
You can design your structure so that:
The trust owns the equity (for protection and estate planning), while you serve as manager or officer (for operational control), or
A trusted family member, professional trustee, or advisory board holds certain control powers to ensure continuity beyond your active involvement
By carefully designing these roles, you can retain meaningful influence over the business while reducing personal exposure and positioning the business for long-term stability and tax efficiency.
Using Different Classes of Ownership Interests
In some cases, you can issue different classes of ownership—such as voting and non-voting interests or preferred and common units—and allocate them strategically among individuals and trusts. This allows you to:
Keep voting control concentrated while transferring economic interests to heirs or trusts for tax planning
Facilitate gradual ownership shifts without disrupting management or decision-making
Potentially apply valuation discounts when transferring minority, non-controlling interests (subject to professional valuation and tax rules)
📌 Key Takeaway: Separating ownership and control is not about hiding assets—it is about structuring them intelligently within the law. Big Life Financial works with your legal team to explore options like voting vs. non-voting interests, management companies, and trustee roles that align with your goals.
Structuring Entities for Efficiency and Protection
Trusts are only one part of the puzzle. The way you structure your business entities—LLCs, corporations, holding companies, and related entities—has a major impact on both taxation and asset protection. Instead of a single entity doing everything, many entrepreneurs benefit from a multi-entity architecture designed around risk, income streams, and long-term plans.
The Role of Holding Companies and Operating Companies
A common strategy is to separate your business into:
A holding company that owns valuable assets—such as intellectual property, brand rights, or ownership stakes in operating companies—and
One or more operating companies that handle day-to-day activities, employees, and customer interactions (and therefore assume more liability risk)
This structure can:
Shield core assets from lawsuits targeting a specific operating company
Simplify the sale of a particular division or brand while keeping others intact
Enable tax-efficient flows of income via management fees, royalties, or intercompany leases (within legal and economic substance requirements)
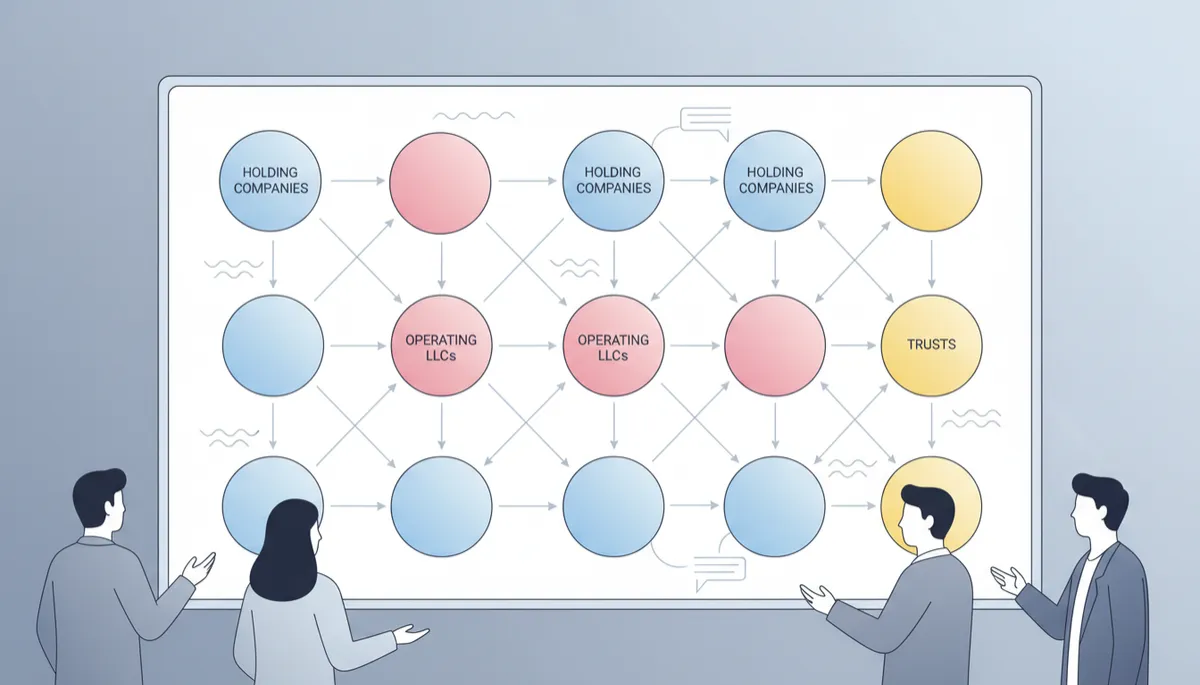
-tone photograph of a whiteboard diagram showing holding companies, operating LLCs, and trusts...
Carefully layered entities can separate risk, optimize taxes, and support long-term exits.
Matching Entity Types to Income and Exit Goals
Different entity types—such as S corporations, C corporations, and LLCs taxed as partnerships—offer distinct tax treatments. For example, some structures may be better suited for:
Reducing self-employment taxes on active income (e.g., S corporation wages and distributions planning)
Retaining earnings inside a company for reinvestment or future sale (e.g., C corporation strategies, subject to double taxation considerations)
Allocating income, losses, and depreciation flexibly among partners (e.g., LLCs taxed as partnerships)
The “best” entity is rarely universal. It depends on whether you plan to:
Hold the business long-term for cash flow
Sell to a strategic buyer or private equity group in a few years
Transition ownership gradually to family members or key employees
💡 Pro Tip: Re-structuring entities shortly before a sale can create tax friction or scare off buyers. Working with a planning-focused team like Big Life Financial early can help you choose structures that support your likely exit paths from the start.
Risk Segmentation and Asset Isolation
Another key principle is risk segmentation. Instead of putting all operations and assets into a single entity, you can isolate higher-risk activities in separate entities. For example:
Real estate used by the business can be owned in a separate LLC and leased to the operating company, helping to shield the property from operating company lawsuits.
Different product lines with varying liability profiles can be split into distinct entities to contain potential claims.
Intellectual property can be owned by a holding company and licensed to operating entities, separating valuable intangible assets from front-line risk.
When trusts are layered on top of these entities, you can achieve multiple layers of protection: entity-level liability shields plus trust-level separation from personal assets. Big Life Financial often helps clients map this out visually so you can see exactly how your business, trusts, and personal holdings interact.
Coordinating Tax, Legal, and Financial Advisors
Even the best-designed structure can fail if your advisory team is not on the same page. Tax professionals, attorneys, and financial strategists often work in silos—each optimizing their own area without a holistic view. The result can be:
Tax strategies that conflict with legal asset protection goals
Estate plans that ignore business realities or cash flow needs
Investment plans that do not reflect entity structures or trust distribution rules
The Power of a “Quarterback” Advisor
Business owners often benefit from having a “quarterback” advisor whose role is to coordinate the moving pieces and keep the big picture in focus. This is a core part of what Big Life Financial provides: they help you clarify your goals, then work with your CPA, attorney, and other specialists to align strategies around those goals.
In practice, this can include:
Facilitating joint meetings where tax, legal, and financial perspectives are discussed together rather than separately
Stress-testing proposed structures for real-world scenarios—lawsuits, audits, disability, death, or unexpected opportunities
Ensuring that documents (operating agreements, trust documents, buy-sell agreements) reflect the tax and financial strategies you intend
Integrating Personal and Business Planning
Another common gap is the disconnect between business planning and personal financial planning. Your business is often your largest asset and primary income source, so its structure directly affects your:
Retirement income and exit proceeds
Family’s security if something happens to you
Ability to invest in other assets—real estate, market portfolios, or alternative investments
Big Life Financial’s philosophy is to look at your entire financial ecosystem. They help you evaluate questions like:
How much cash flow should stay inside the business vs. be moved to protected personal or trust accounts?
Are you overexposed to business risk relative to your net worth and stage of life?
How can insurance, retirement plans, and other tools integrate with your entity and trust structures?
⚠️ Warning: Copying someone else’s structure or relying on internet templates can backfire. Laws vary by state and country, and what works for one business can be risky or ineffective for another. Always involve qualified tax and legal professionals when implementing advanced structures.
A Step-by-Step Framework to Start Restructuring Wisely
If you are realizing your current setup may not be optimized, you do not have to fix everything overnight. Here is a practical framework, often used by Big Life Financial with clients, to move from reactive to strategic ownership design:
Clarify your “big life” goals. Are you building to sell, to pass down, or to create semi-passive income? How important are control, privacy, and legacy? Your structure should serve these goals, not the other way around.
Map your current reality. List all entities, ownership percentages, key contracts, and existing trusts or estate documents. Many owners discover inconsistencies or outdated documents at this stage.
Identify major risks and opportunities. Where are you most exposed to lawsuits or creditor claims? Where are you overpaying in taxes or missing deductions? Where is succession unclear or fragile?
Design a target structure. With your advisory team, sketch a future-state diagram: which trusts will own which entities, where holding companies fit, and how income will flow. This is where Big Life Financial’s visual and strategic planning tools can be especially helpful.
Phase in changes thoughtfully. Implement the new structure in stages to manage tax implications, legal costs, and operational disruption. Start with the most impactful and time-sensitive pieces—such as asset protection for high-risk activities or critical trust funding.
Maintain and review regularly. Laws change, your business evolves, and your personal goals shift. Schedule periodic reviews with your advisory team to keep your structure aligned and compliant.
How Big Life Financial Fits Into Your Planning Team
Big Life Financial is not a law firm or a traditional CPA practice. Instead, they specialize in strategic design—helping entrepreneurs use tools like trusts, multi-entity structures, and coordinated tax strategies to keep more of what they earn and protect what they are building. Their role is to:
Educate you on options in clear, practical language so you can make informed decisions
Help you articulate your long-term vision for wealth, freedom, and legacy—the “big life” you actually want
Coordinate with your existing professionals or connect you with trusted attorneys, CPAs, and specialists as needed
Instead of piecemeal advice, you get a cohesive strategy that weaves together:
Trust structures tailored to your family and goals
Entity design for tax efficiency and risk management
Cash flow, investment, and insurance strategies that support both your business and personal balance sheet
“The goal is not just to pay less tax this year. It is to design a life where your business, your money, and your structures all work together to give you more options and more security.”
— Philosophy shared by the team at Big Life Financial
Bringing It All Together: Your Next Steps
Designing business ownership structures for tax efficiency and asset protection is not just for billionaires or giant corporations. If you own a profitable business—or are on your way there—you already have enough at stake to justify thoughtful planning. By:
Using trusts to hold business interests and shape how wealth flows to your family and causes you care about
Separating ownership and control to unlock strategic tax planning and stronger protection
Structuring entities to segment risk, optimize income flows, and support your exit or succession plans
And coordinating your advisors so tax, legal, and financial strategies reinforce each other
you can transform your business from a source of income into a powerful engine for long-term wealth and security.
💡 Pro Tip: The best time to start optimizing your structure is before a major event—like rapid growth, a big acquisition, or an exit. The second-best time is now. Even incremental changes can compound into significant tax savings and stronger protection over time.
If you are ready to explore what a more intentional structure could look like for your situation, consider connecting with Big Life Financial. Their team can help you see the full picture, coordinate with your existing advisors, and design a plan that supports the life you want—not just the business you run.
You have worked hard to build your company. With the right ownership structures, you can make sure that effort translates into lasting, protected, and tax-efficient wealth—for you, your family, and the legacy you want to leave. We've gathered the key insights here, but there's plenty more to explore. The full conversation offers additional stories, perspectives, and ideas that bring the discussion to life.
