Business Owner Cash Flow & Growth Plan Guide
Business Owner Financial Planning, Cash Flow Strategy
Creating a Growth and Cash Flow Plan as a Business Owner
As a business owner, your personal and business finances are deeply connected—but they should not be identical. A thoughtful cash flow plan for business owners helps you grow your company, protect your household, and steadily build long-term wealth. In this guide, we’ll walk through how to create a practical Financial Growth Plan that includes money outside the business, a clear Cash Flow Strategy, and a roadmap that aligns with where you are in life today. We’ll also share Wealth Management Tips you can start using right away to support both your business cash flow and your personal future.
Why Every Business Owner Needs a Cash Flow Plan Beyond the Business
Many entrepreneurs pour everything back into the company—time, energy, and every spare dollar. While that drive fuels growth, it can quietly create risk. If most of your net worth is tied up in one asset—your business—you’re exposed to industry shifts, economic cycles, and unexpected events that are outside your control. A strong wealth growth strategy includes building assets and cash flow streams that live outside your company, so your future is not dependent on a single outcome, like a sale or exit.
At BLF, we often see owners who have thriving businesses but feel financially insecure at home. The solution is not to slow growth—it’s to design a personal cash flow planning framework that uses your business success as a powerful engine, while steadily converting some of that success into personal wealth and flexibility. Think of it as paying your “future self” a dividend, not just reinvesting for today.
Step 1: Develop a Plan for Money Outside the Business
Developing a plan for money outside the business starts with a simple but powerful question: What portion of each year’s profit will I intentionally move into personal wealth? This is the foundation of effective business owner financial planning. Instead of waiting for “leftover” cash, you define a target and build your decisions around it—just as you would with any other strategic priority in your company.
1. Decide on a Personal Distribution Policy
A distribution policy is your commitment to move a specific percentage or dollar amount of profits into personal accounts each year. For example:
30% of annual after-tax profit goes to the owner(s) personally, 70% stays in the business for reinvestment and reserves, or
A fixed annual amount (for example, $150,000) is transferred to personal accounts, with any excess profit reinvested.
This simple rule transforms your cash flow plan for business owners from reactive to intentional. It also creates a predictable flow of funds you can use to build savings, investments, and other assets outside your company.
2. Build a Personal Safety Net First
Before you focus on aggressive investing, your first goal is resilience. A strong Financial Growth Plan for owners includes:
Emergency fund: 6–12 months of personal living expenses in cash or high-yield savings, separate from business accounts.
Risk management: Appropriate insurance coverage (life, disability, liability) so a personal crisis doesn’t force a business fire sale.
This personal foundation means you’re less likely to pull money out of the business at the worst possible time, and you can weather both personal and business storms with more confidence.
3. Diversify Beyond Your Company
Once your safety net is in place, your wealth growth strategy should gradually diversify your net worth. Common building blocks include:
Retirement accounts: 401(k), SEP IRA, Solo 401(k), or other tax-advantaged plans for business owners.
Taxable investment accounts: Flexible brokerage accounts for long-term investing and future opportunities.
Real estate or other assets: Carefully selected properties or alternative investments that fit your risk profile.
The goal is not to replace your business, but to ensure that if your industry changes or you choose to step away, your lifestyle and long-term goals remain protected.
💡 Pro Tip: Treat your future self like a key stakeholder. When you review profits each year, ask: “How much are we returning to the owner’s personal balance sheet?”
Step 2: Growing and Managing Business Cash Flow with Intention
A powerful Cash Flow Strategy doesn’t just focus on surviving the slow months—it actively supports growth, stability, and owner distributions. Strong Business Cash Flow allows you to invest in people, systems, and marketing, while still paying yourself and building personal wealth. To do this, you need visibility, structure, and habits that keep cash working in the right places at the right times.
1. Map Your Cash Flow Rhythm
Start by understanding how money actually moves through your business month by month. A simple 12-month cash flow forecast can show:
When revenue is earned versus when it is collected.
Fixed expenses (rent, salaries, software) versus variable costs tied to sales or production.
Seasonal patterns or recurring cash crunches you can plan for in advance.
This forecast doesn’t need to be perfect. Even a basic, realistic view of inflows and outflows turns guesswork into data and helps you make better decisions about hiring, inventory, marketing, and owner pay.
2. Separate Operating Cash, Reserves, and Growth Capital
One of the most effective Wealth Management Tips for entrepreneurs is simple: give every dollar a “job” and a “home.” Instead of letting all cash sit in a single operating account, consider three primary buckets:
Operating cash: The money you need to run the business smoothly over the next 30–60 days.
Reserves: 2–6 months of core expenses held in a separate account for stability and emergencies.
Growth capital: Funds intentionally set aside for expansion—new hires, equipment, marketing campaigns, or acquisitions.
When you know how much belongs in each bucket, it becomes much easier to see what is truly “excess” and available for owner distributions that support your personal cash flow planning.
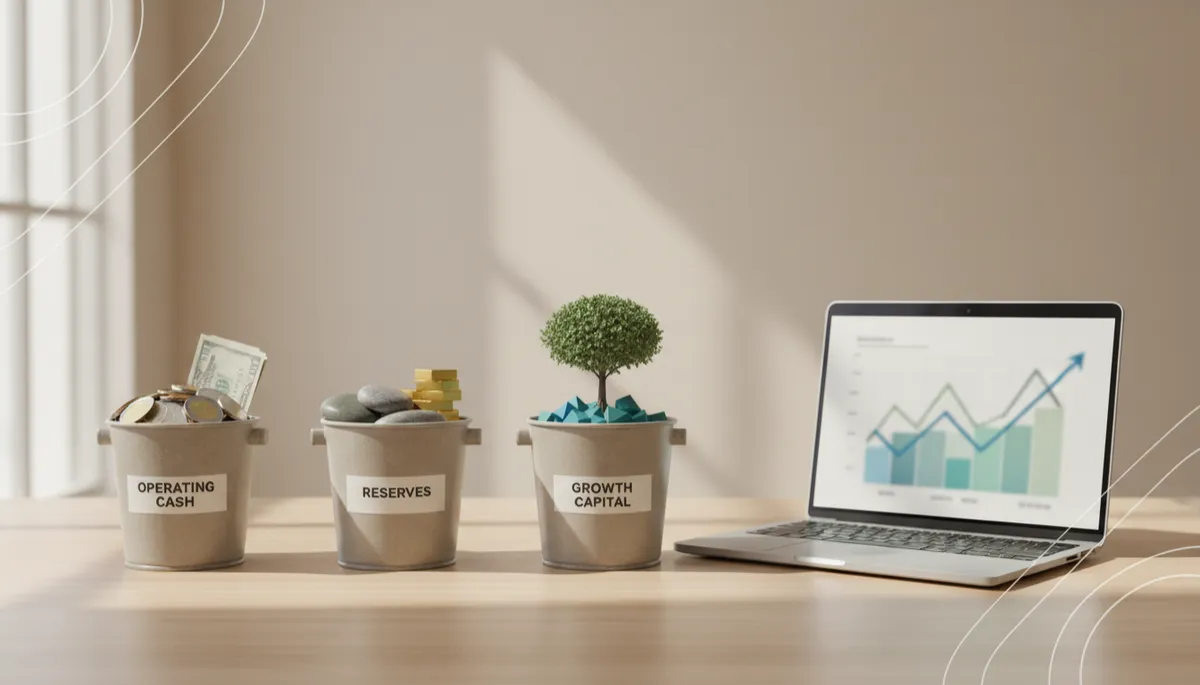
Clear cash buckets help owners see what can safely support personal wealth goals.
3. Tighten the Levers That Drive Business Cash Flow
To grow and manage Business Cash Flow, focus on the levers you can influence:
Receivables: Shorten payment terms, incentivize early payment, and follow up consistently on overdue invoices.
Payables: Negotiate favorable terms with key vendors without damaging relationships or reliability.
Pricing and margins: Regularly review pricing, discounting, and cost of goods to protect profitability as you grow.
Even small improvements in these areas can significantly increase free cash flow—the lifeblood that funds both reinvestment and your personal Financial Growth Plan.
4. Make Cash Flow Reviews a Standing Habit
A one-time cash flow analysis is helpful; a recurring rhythm is transformative. Consider:
Weekly check-ins on bank balances, upcoming payments, and expected deposits.
Monthly reviews of profit, cash flow, and how much you moved into your personal accounts.
Quarterly strategy sessions focused on growth investments, debt, and owner distributions.
Over time, these habits turn cash flow from a source of stress into a strategic tool that supports every part of your business owner financial planning.
Step 3: Aligning Your Financial Plan with Where You Are in Life
A powerful cash flow plan for business owners is not one-size-fits-all. Your ideal Cash Flow Strategy should reflect your age, family situation, business stage, and personal goals. The right balance between reinvesting in the company and building money outside the business will change over time. Aligning your plan with your life stage ensures you are not only building a valuable business, but also a life you actually want to live.
Early Stage: Building Momentum and Protecting the Foundation
In the early years, cash often feels scarce and every dollar seems to belong in the business. At this stage, your Financial Growth Plan should focus on:
Achieving consistent profitability and stabilizing Business Cash Flow.
Building a modest personal emergency fund, even if it starts small.
Putting basic protections in place (insurance, legal structure, simple estate documents).
Your wealth growth strategy here might be as simple as committing a small, fixed amount each month to a retirement or investment account, and increasing it as the business grows. The habit matters more than the initial size.
Growth Stage: Balancing Reinvestment and Personal Wealth
As your business matures and cash flow becomes more predictable, you can be more intentional about balancing growth with personal wealth building. In this stage, effective business owner financial planning often includes:
Setting a clear distribution policy and sticking to it, even during strong growth years.
Increasing contributions to retirement plans and taxable investment accounts as profits rise.
Evaluating whether to pay down debt, invest in new opportunities, or accelerate personal savings based on your goals.
This is often where a more formal personal cash flow planning process becomes valuable. You can map out your lifestyle needs, savings targets, and business reinvestment goals on a single page, so you can see how each decision supports your long-term vision.
Pre-Exit and Transition: Turning Business Value into Personal Freedom
As you approach a potential sale, succession, or step-back from daily operations, your Cash Flow Strategy shifts again. The focus moves from maximizing growth at all costs to converting business value into durable personal wealth. Key priorities often include:
Clarifying your ideal timeline, lifestyle, and legacy goals after the transition.
Stress-testing your personal Financial Growth Plan: Will projected assets and cash flow support your desired lifestyle?
Coordinating tax planning, estate planning, and investment strategy around a potential liquidity event.
At this stage, the quality of your earlier decisions—how consistently you built money outside the business and strengthened Business Cash Flow—can dramatically increase your options and peace of mind.
💡 Pro Tip: Revisit your plan annually. Your life, goals, and business will evolve. Your cash flow plan should evolve with them, not stay frozen in last year’s realities.
Bringing It All Together: A Simple Framework You Can Start Using Now
To turn these ideas into action, it can help to see a straightforward framework. Here is a practical way to structure your cash flow plan for business owners in three steps:
Clarify your life stage and priorities. Are you in early growth, scaling, or thinking about exit? What matters most in the next 3–5 years—aggressive expansion, family time, debt reduction, or financial independence?
Design your distribution and savings rules. Decide how much profit will go to operating needs, reserves, growth, and personal wealth each year. Write it down and treat it like a core part of your Business Cash Flow plan.
Build your personal wealth engine. Use those distributions to fund your emergency savings, retirement accounts, and long-term investments. Review progress at least annually and adjust as your life and business evolve.
This approach doesn’t require perfect forecasting or complex models. It simply asks you to make conscious choices about how your business supports your life, and to use your Cash Flow Strategy as the bridge between the two.
How BLF Can Support Your Growth and Cash Flow Plan
Creating a cohesive plan that connects your business finances, personal goals, and long-term wealth can feel overwhelming—especially when you’re already leading a company. That’s where a coordinated, owner-focused approach to business owner financial planning becomes invaluable. At BLF, we help entrepreneurs design and implement a Financial Growth Plan that:
Clarifies your goals at home and in the business, so your decisions support both.
Builds a practical, numbers-backed Cash Flow Strategy for your company, including reserves and growth capital.
Creates a personal wealth roadmap that steadily moves money outside the business into a diversified, long-term plan.
Whether you’re just beginning to see consistent profits or preparing for a major transition, you don’t have to navigate these decisions alone. With the right guidance and a clear structure, your business can be more than a demanding job—it can become the engine that funds a secure, flexible, and meaningful life.
Final Thoughts: Own Your Cash Flow, Own Your Future
Your business is one of the most powerful tools you have for creating wealth, impact, and freedom. But without a thoughtful cash flow plan for business owners, it’s easy to wake up years later with a successful company and a personal financial picture that feels fragile or uncertain. By:
Developing a clear plan for money outside the business,
Growing and managing Business Cash Flow with intention, and
Aligning your financial plan with where you are in life,
you create a path where your company’s success steadily translates into real-world security and options for you and the people you care about. That is the heart of intentional personal cash flow planning and effective Wealth Management Tips for business owners: using today’s effort to build tomorrow’s freedom, step by step, year after year.
You don’t have to take everything from this article at face value. Listen, think it through, and see what resonates with you. The video gives you another perspective and more context to consider on your own terms.
