Transform Business Income to Personal Wealth
Financial Planning, Business Income to Personal Wealth
Turning Business Income Into Personal Wealth: A Practical Guide for Entrepreneurs
Your business may be thriving, but is it actually making you wealthy? In this guide, we’ll break down how to move business income to personal wealth, create a clear plan for money you pull from the business, and finally make money work for you instead of always working for it.
Why Business Success Doesn’t Automatically Equal Personal Wealth
Many entrepreneurs assume that a growing company automatically leads to a wealthy life. But without a deliberate business owner wealth strategy, it’s easy to end up “asset rich, cash poor,” or worse, have your entire future tied to one business that could change overnight.
True wealth building for entrepreneurs means intentionally moving value from the business into your personal world—where it can support your family, fund your goals, and eventually give you the freedom to work because you want to, not because you have to. That’s the heart of turning business income to personal wealth.
💡 Big Life Insight: Your business is a powerful engine, but your personal balance sheet is the destination. Big Life Financial focuses on helping owners make that shift intentionally.
Step 1: Separate You From Your Business (On Paper First)
The foundation of any solid Financial Planning strategy for entrepreneurs is a clear line between your business finances and your personal finances. Without that separation, it’s almost impossible to see how much wealth the business is really creating for you personally.
Maintain distinct business and personal bank accounts and credit cards.
Pay yourself a consistent owner’s draw, salary, or distribution schedule, not random transfers whenever cash feels available.
Track your personal net worth separately from the value of the business.
This is where Business Wealth starts to become Personal Finance. Instead of seeing the business as “your money,” you begin to see it as a tool that pays you—and that you can gradually convert into independent, diversified wealth.
Step 2: Moving Money From the Business Into Personal Wealth (Intentionally)
Moving money from the business into personal wealth isn’t just about taking a bigger paycheck. It’s about designing a repeatable system that steadily transfers risk and reward from your company to your personal life. Think of your business as a faucet and your personal wealth accounts as the buckets you’re filling on purpose.
Decide How Much the Business Can Safely Pay You
Start by understanding your business cash flow. After covering operating expenses, taxes, and a healthy profit margin, what’s left that can reliably be paid out to you each month or quarter? This is the raw material you’ll use to turn income into wealth.
Set a baseline salary or draw that covers your personal lifestyle needs.
Add a second layer: targeted distributions earmarked specifically for investments and long-term wealth building.
💡 Pro Tip: Many Big Life Financial clients create a simple rule like “10–20% of every profitable month automatically moves from business accounts into personal wealth accounts.”
Automate the Transfer From Business to Personal
Once you know what the business can safely pay you, automate it. Treat these transfers as non‑negotiable “wealth bills” you pay to your future self. This is a simple but powerful business owner wealth strategy that removes emotion and guesswork from the process.
Schedule recurring transfers from your business account to your personal account on a specific day each month.
From your personal account, set up automatic contributions into investment, savings, and protection vehicles.
Step 3: Creating a Plan for Money Pulled From the Business
Pulling money out of the business without a plan is one of the fastest ways to stall your progress. The goal is to move from random withdrawals to a thoughtful Wealth Management strategy that aligns with your life goals. Every dollar that leaves the company should have a clear job to do in your personal world.
Give Every Dollar a Destination
A simple framework Big Life Financial often uses is to divide personal inflows into four broad buckets. You can adjust percentages, but the structure helps ensure that business income truly becomes personal wealth:
1. Lifestyle: Housing, food, travel, and the life you enjoy today.
2. Safety: Emergency fund, insurance, and reserves that protect your family if the business slows down.
3. Growth: Investments that can grow independently of your business—stocks, bonds, real estate, or other diversified assets.
4. Freedom: Long‑term retirement and passive income strategies that will eventually replace the need to work.
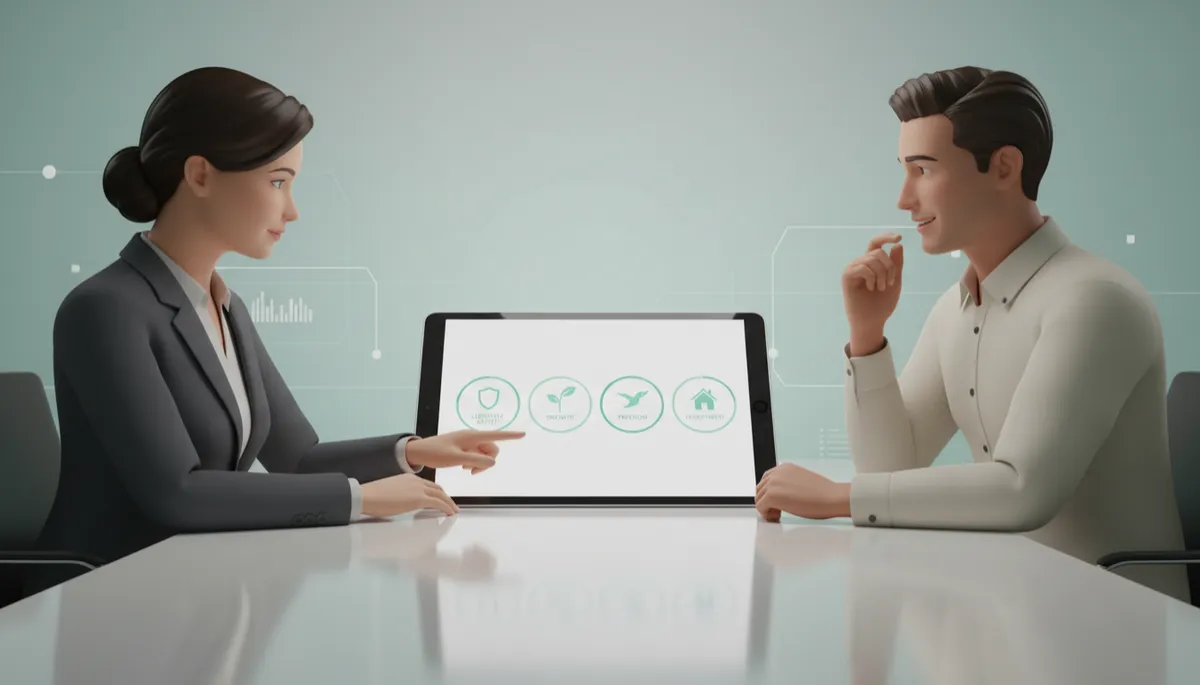
Clear buckets turn random withdrawals into a repeatable wealth-building system.
Align Your Plan With Your “Big Life” Goals
Numbers only matter when they support the life you actually want. That’s why a strong Financial Planning process starts with questions like:
When do you want the option to step back from your business—or sell it entirely?
What kind of lifestyle do you want to protect for your family, no matter what happens in the business?
How important are flexibility, travel, philanthropy, or leaving a legacy?
With those answers, you can design a business income to personal wealth plan that feels meaningful, not just mathematical. This is the kind of work Big Life Financial does with clients every day—connecting spreadsheets to real‑life dreams.
Step 4: Making Money Work for You (Instead of Only Working for Money)
As a business owner, you’re used to earning money by solving problems and putting in effort. But long‑term wealth building for entrepreneurs requires a shift: learning to let your money earn money, even when you’re not working. This is where Wealth Management really comes into play.
Build Multiple Streams Beyond Your Business
Your company might be your primary income engine today, but your personal wealth should be diversified. When you consistently turn income into wealth, you can gradually build:
Investment portfolios that grow through compounding, not just your effort.
Real estate or other assets that generate rental or passive income.
Tax‑advantaged retirement accounts that quietly build a future income stream.
Over time, these outside assets can grow to the point where your lifestyle is no longer fully dependent on the business. That’s the moment when you truly feel that money is working for you.
Use Systems, Not Willpower
Entrepreneurs are busy. Relying on willpower to remember to invest or save is a losing game. Instead, build a system that quietly handles your Personal Finance in the background:
Automatic contributions into diversified investment accounts each month.
Pre‑scheduled reviews with a financial consultant who understands Business Wealth and tax strategy.
Clear thresholds for when to increase your contributions as the business grows.
💡 Pro Tip: Treat your future self like a non‑negotiable business vendor. You “pay” that vendor first through automatic investing, then live on what’s left.
Balancing Reinvesting in the Business vs. Building Personal Wealth
One of the toughest decisions for entrepreneurs is choosing between reinvesting profits into growth and moving money into personal assets. Both matter. The key is balance and clear priorities within your overall business owner wealth strategy.
When It Makes Sense to Reinvest Heavily
If your business is in a high‑growth phase and each dollar you reinvest reliably produces outsized returns, it can be wise to lean into that growth. But even then, consider setting a minimum percentage—say 10–15% of profits—that must leave the business and support your personal wealth plan, no matter how exciting the growth opportunities are.
When to Prioritize Personal Wealth Building
As your company matures, the risk of being overexposed to one asset—your business—often becomes more obvious. If most of your net worth is tied up in the company, it’s usually time to increase the flow from business income to personal wealth. That might look like:
Larger, scheduled distributions to fund investment accounts and real estate.
Building a “freedom fund” that could support you for several years if you decided to exit.
Exploring succession, sale, or partial exit strategies with a financial consultant.
Protecting What You’re Building: Risk, Taxes, and Safety Nets
Turning business income to personal wealth isn’t just about growth; it’s also about protection. A smart Wealth Management plan for entrepreneurs includes safety nets so one setback doesn’t undo years of progress.
Build a Personal and Business Emergency Buffer
Aim to hold several months of expenses in both business and personal accounts. This buffer gives you breathing room during slow seasons or unexpected events and keeps you from raiding long‑term investments just to cover short‑term problems.
Be Strategic About Taxes
Taxes are often one of the largest expenses for successful entrepreneurs. Coordinating Business Wealth decisions with your personal tax strategy can free up more cash to invest. This might include:
Choosing the right business entity and compensation structure.
Using retirement plans or other tax‑advantaged accounts designed for business owners.
Coordinating with a tax professional and a financial consultant so your strategies work together.
Putting It All Together: A Simple Business Owner Wealth Strategy
To recap, turning business income to personal wealth doesn’t require complex tricks. It requires clarity, consistency, and a plan. Here’s a streamlined version you can adapt:
Separate business and personal finances so you can see clearly what the business is truly doing for you.
Decide a safe, consistent payout from the business that supports both your lifestyle and your wealth goals.
Automate transfers from business accounts into personal accounts, and then into specific investment and savings vehicles.
Give every dollar a job using clear buckets: lifestyle, safety, growth, and freedom.
Build assets outside the business so money starts working for you through compounding and passive income.
Protect and optimize with emergency funds, smart tax planning, and risk management.
How Big Life Financial Can Support Your Journey
You don’t have to figure all of this out on your own. As a financial consultant focused on entrepreneurs, Big Life Financial helps business owners design a personalized plan to turn income into wealth in a way that fits their goals, risk tolerance, and stage of business.
Together, you can map out how much money to move from the business into personal wealth each month, how to allocate those dollars across lifestyle, safety, growth, and freedom, and how to ensure your money is working as hard for you as you’ve worked to earn it. That’s the essence of wealth building for entrepreneurs—and the path to a truly “big life” beyond your business.
📌 Key Takeaway: A successful company is only half the story. The real win is a life where your business supports your wealth—and your wealth supports your freedom.
Some of the most interesting insights happen between the main points—the stories, examples, and thoughts that come up along the way. The video gives you a chance to experience more of that conversation for yourself.
